

A quick interruption from me, based on great feedback & demand since the success of the Kintsugi sponsored issue, The Nexus is now open for corporate sponsorship, click above and contact me if you’re interested.
🎶Working 9 to 5🎵
Grant Thornton just paid $5 billion to move from 9th to 5th place in the accounting firm rankings. Here’s what its CBIZ deal tells us about who really controls tax technology buying decisions from here.
WHAT JUST HAPPENED
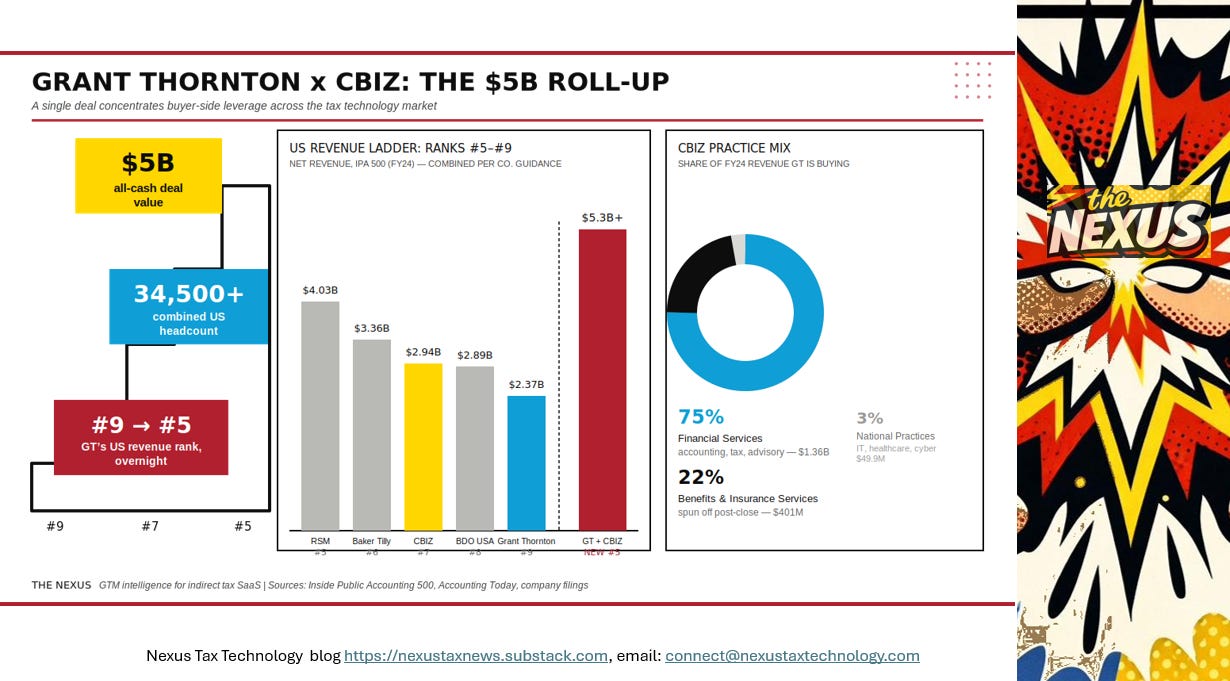
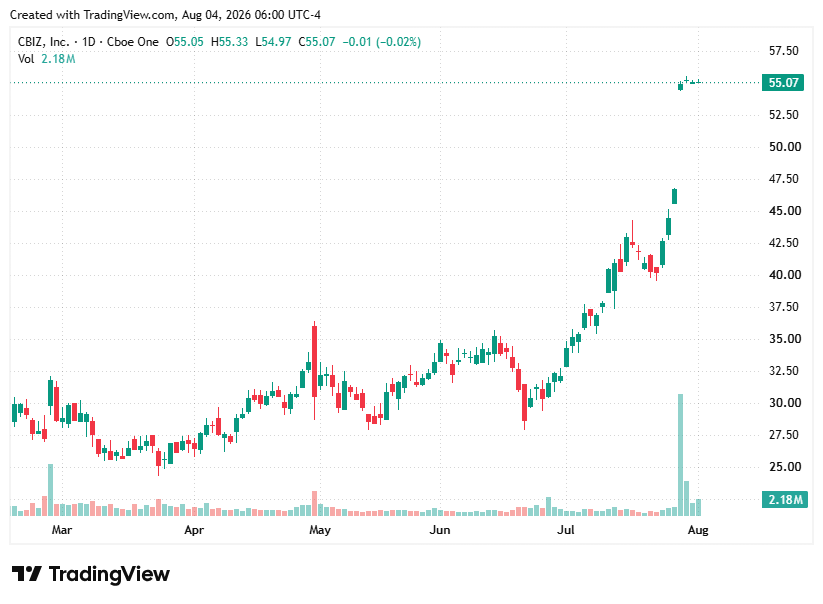
On 29 July 2026, Grant Thornton announced an all-cash, $5 billion acquisition of CBIZ (NYSE: CBZ), backed by additional equity from New Mountain Capital. It’s the largest deal the accounting profession has seen in more than 25 years, expected to close Q4 2026 pending shareholder and regulatory approval.
The combined firm becomes the fifth-largest professional services, tax and advisory provider in the US — behind only Deloitte, EY, KPMG and PwC — with north of $5 billion in domestic revenue, $7.5 billion globally, and 34,500+ people. Grant Thornton walked in at #9 on Accounting Today’s 2026 Top 100 ($2.5bn revenue); CBIZ was #8 ($2.8bn). One transaction, one rung skipped past RSM and BDO.
WHAT CBIZ ACTUALLY IS
CBIZ isn’t a tax boutique — it’s a diversified middle-market platform, and that matters for how this plays out:
→ Scale: 10,000+ team members across 160+ locations in 22 major US markets. Founded 1987, Independence, Ohio. Until this deal, the only publicly traded pure accounting services provider in the country.
→ Financial Services ($1.36bn, FY24): core accounting, tax compliance, transaction and risk advisory, valuation, government healthcare compliance — the practice group that actually overlaps with GT’s tax business.
→ Benefits and Insurance Services ($401m, FY24): group health, P&C brokerage, retirement advisory. This unit is being spun off post-close as an independent company, separately backed by New Mountain.
→ National Practices ($49.9m, FY24): IT/hardware and healthcare consulting, plus a cyber risk program — the technology-delivery muscle GT is buying alongside the client book.
→ Track record: grown through 25+ acquisitions in a decade, including the $2.3bn Marcum LLP buy in November 2024 that made CBIZ #7 in the first place. This firm was already a serial acquirer before GT acquired it.
THE PE X ACCOUNTING PLAYBOOK, CONFIRMED
This isn’t a one-off — it’s the second act of a strategy that started when New Mountain Capital took roughly 60% of Grant Thornton’s US arm in May 2024. The FT called that investment a war chest for acquisitions at the time. CBIZ is that war chest being spent.
Now we’ve seen the playbook run in the software industry a lot,Most notably with SOVOS, Avalara to an extent, it’s also being run by Alphatax as we speak. The mechanic is consistent — buy a platform, bolt on targets for three to five years, expand the EBITDA multiple from mid-single digits to double digits at entry, exit at the top.
Accounting M&A hit a record 194 deals in 2025 — up 26% year-over-year — and it’s still climbing in 2026. Accounting was a fragmented, founder-owned industry for decades. It isn’t anymore.
Accounting M&A hit a record 194 deals in 2025 — up 26% year-over-year — and it’s still climbing in 2026.
WHAT IT DOES TO TAX TECHNOLOGY
No tech vendor changes hands in this deal — They all keep competing exactly as they did on 28 July. What changes is who’s sitting across the table from them. What happens next?
→ The mid-market GTM battle gets sharper. CBIZ’s client base is exactly the segment Avalara, Kintsugi, Anrok and Sphere are fighting to own. A preferred-vendor bundle pushed through that book reshapes GTM math for anyone selling below enterprise.
→ Global reach is being built in parallel. GT has been adding member firms — Australia, New Zealand, Luxembourg, UAE — alongside this deal. That’s a platform positioning for multinational VAT/GST advisory, putting it on a collision course with the Big Four’s grip on ONESOURCE and Sovos channel relationships.
For the Big Four — Deloitte, PwC, EY and KPMG this deal isn’t an existential threat, but it does narrow the gap on an axis mid-market clients actually feel: a client that used to default to a Big Four name purely for scale now has a $5bn+ alternative with matching resources, and all four firms are already absorbing their own cost pressure and job cuts while GT is adding headcount. Expect the response to show up less in pricing and more in partnership terms — sharper implementation-partner incentives, faster certification cycles, and closer co-marketing with taxtech vendors to keep mid-market indirect tax engagements inside the Big Four tent before GT’s bigger platform starts pulling them out.
ADVICE FOR OPERATORS
→ Vendors: get in front of GT’s national tax leadership now. Post-merger tech-stack decisions get locked in during the first 12–18 months of integration — after that, preferred-partner status calcifies.
→ Don’t treat this as a one-off. RSM and BDO now face a decision point. Once one platform pulls this far ahead on scale, the rest have to answer — expect defensive M&A within 12 months.
→ Rebuild your channel map for concentration, not fragmentation. Selling into CPA firms used to mean reaching many independent decision-makers. That’s inverting. Fewer, bigger, harder-to-reach buying committees are the new default — build your GTM motion for that now, not after the next deal closes.
→ If you’re a GT or CBIZ client: get ahead of the integration, don’t wait for it to land on you. Confirm who owns your engagement through close (expected Q4 2026), ask directly whether your tax technology stack recommendation is under review, and watch for changes to your service team or pricing structure in the first two quarters post-close — that’s when preferred-vendor decisions and staffing reshuffles typically happen, and clients who ask early get more say in the outcome than clients who find out after the fact.
Now to move on to the rest of the issue, next up the spotlight turns on Marosa VAT a serious emerging player in the European VAT technology space, so much so that CCH just paid 112M for them
⭐ Vendor Spotlight: Marosa VAT
Marosa: The Enterprise VAT Backbone Europe’s Big Four Alumni Built the Hard Way
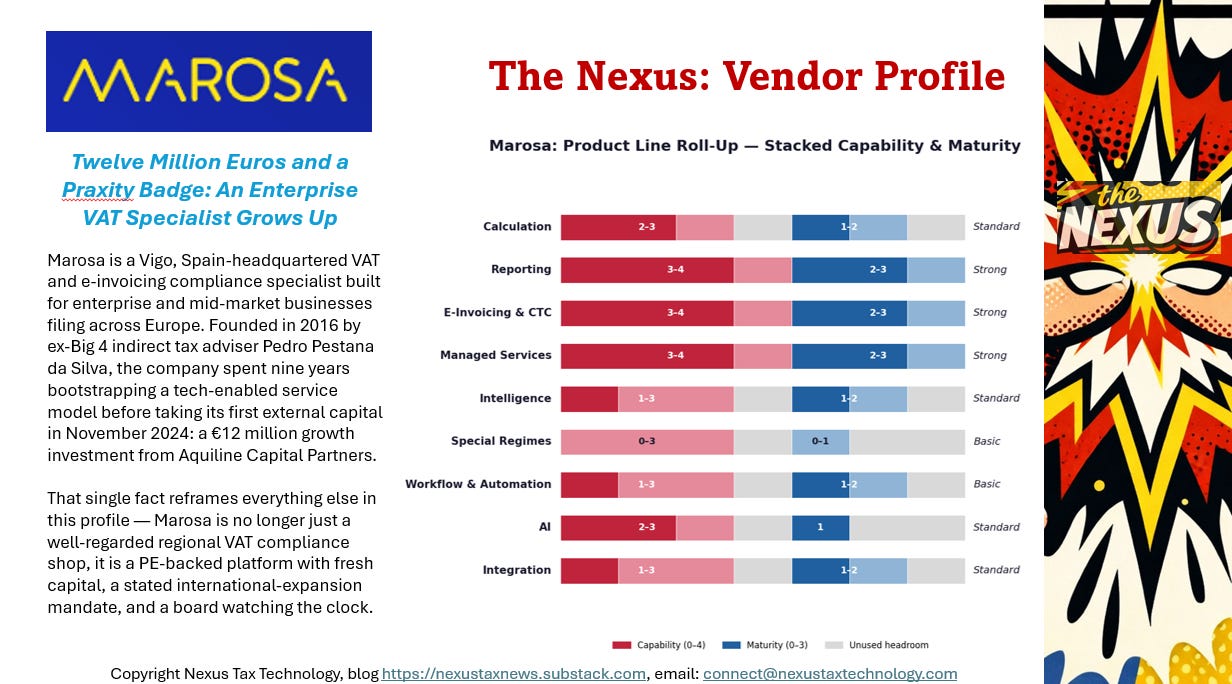
Most challengers in this market chase self-serve marketplace sellers. Marosa did the opposite — nine years of bootstrapped, services-heavy VAT compliance for European enterprises — before Aquiline Capital Partners handed it €12 million in November 2024 to go find out how far that model scales.
WHAT MAROSA ACTUALLY IS
Marosa is a Vigo, Spain-based VAT and e-invoicing compliance platform, VATify, covering VAT/GST returns, SAF-T, Intrastat, e-invoicing and Continuous Transaction Controls across roughly twenty country modules, VAT registration and fiscal representation, and EPR reporting in Germany, France and Spain. Its centre of gravity is Europe and the UK — no US sales-and-use tax, no meaningful APAC or LatAm depth. Headcount estimates are inconsistent across sources (76 to 250–499), and revenue is undisclosed; a bottom-up build from its 1,200+ customers and 40,000+ annual returns points to roughly €20–30M ARR. This is a vendor for mid-market and enterprise finance teams centralising EU/UK VAT across an ERP or shared-service centre, not a self-serve tool for solo sellers.
WHERE IT BEATS THE MARKET BASELINE
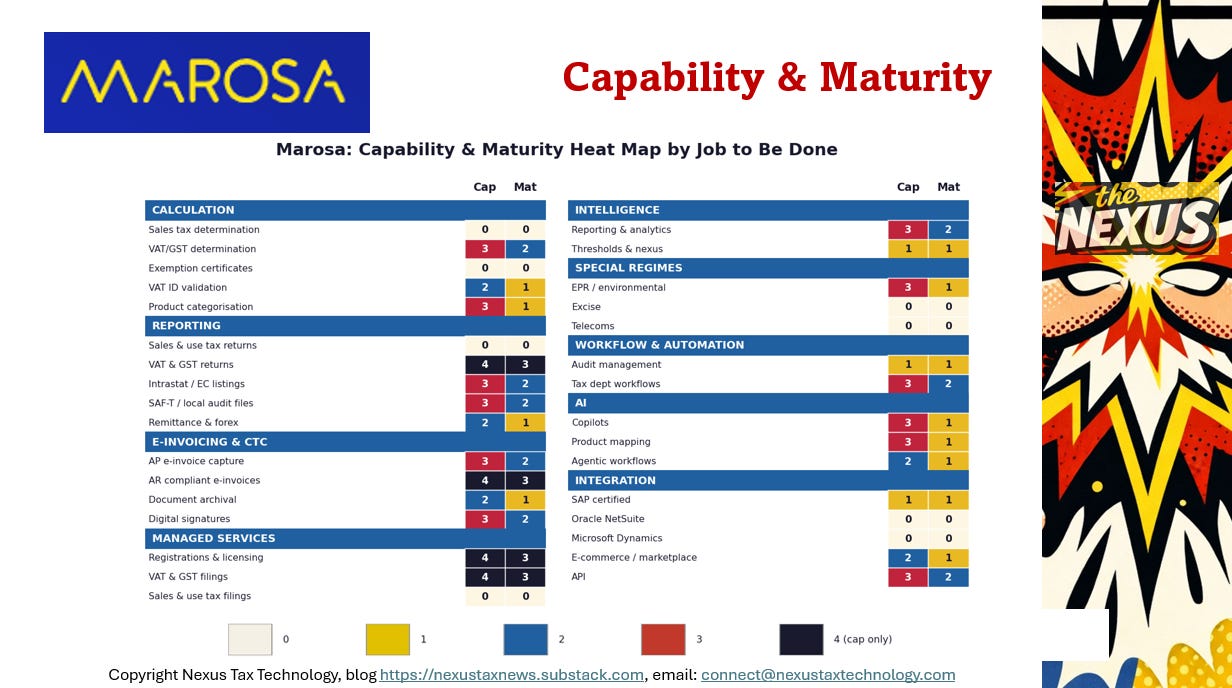
Marosa’s e-invoicing/CTC line is genuinely above baseline: Peppol-certified, accredited under France’s Plateforme Agréée scheme, and documented country-by-country at the technical-format level (FA(3), FatturaPA, XRechnung/ZUGFeRD, SII/VeriFactu). Its AI suite is unusually substantive for this tier — four named, working tools (a natural-language analytics copilot, a knowledge-constrained advisor, an agentic letters-processing tool, a legislation-linked rate engine) rather than one accelerator case study. Reporting and Managed Services are equally strong, backed by real scale evidence. Below baseline: no published pricing anywhere, no verifiable SAP/Oracle NetSuite/Dynamics certification despite generic ERP claims, e-commerce integration limited to Amazon and Stripe, and an ISO 27001 claim that isn’t independently corroborated.
PORTFOLIO ANALYSIS
Growth has been almost entirely organic — EPR, the AI suite, the country-module build-out — plus one inorganic move: absorbing Taxdoo’s VAT-only customer book as that German rival pivots to accounting, a real DACH expansion dressed up as a “partnership.” Reporting is the largest estimated revenue contributor (~40%), with E-Invoicing/CTC (~25%) the fastest-growing line and the clearest destination for Aquiline’s capital. Read: a services-heavy revenue base, expanding into exactly the CTC mandates now accelerating across Europe.
BUSINESS MODEL AND SIZE BAND FITS
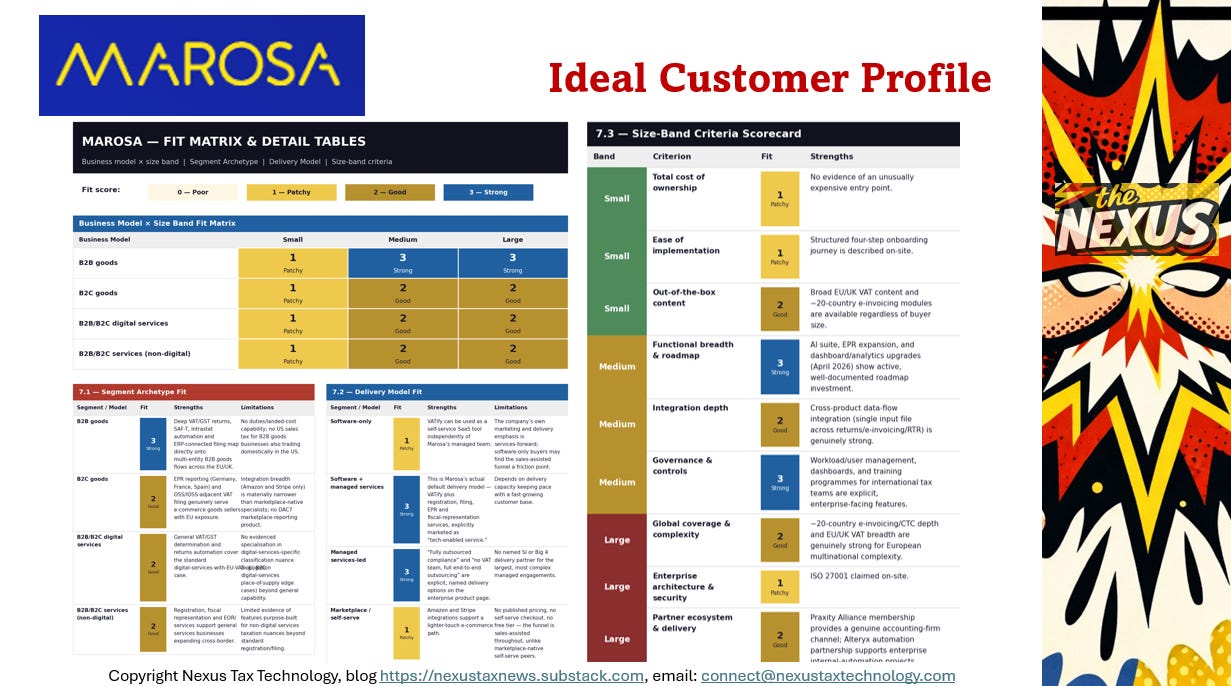
B2B goods: 3 – Strong fit at Medium/Large — ERP-connected filing and Reporting depth are built for this buyer.
B2C goods: 2 – Good fit — EPR and OSS-adjacent filing help, but integration breadth trails marketplace specialists.
B2B/B2C digital services: 2 – Good fit — solid general VAT/GST coverage, no specialist digital-services edge.
B2B/B2C services: 2 – Good fit — registration and fiscal-rep services carry this segment.
Small: 1 – Patchy fit — no published pricing or self-serve signup, a real mismatch for low-touch buyers.
Medium: 2–3 – Good to Strong fit — the clearest sweet spot, backed by active roadmap investment.
Large: 2 – Good fit — strong on European complexity, capped by unverified security posture and thin SI partnerships.
CUSTOMER AND EMPLOYEE SENTIMENTS
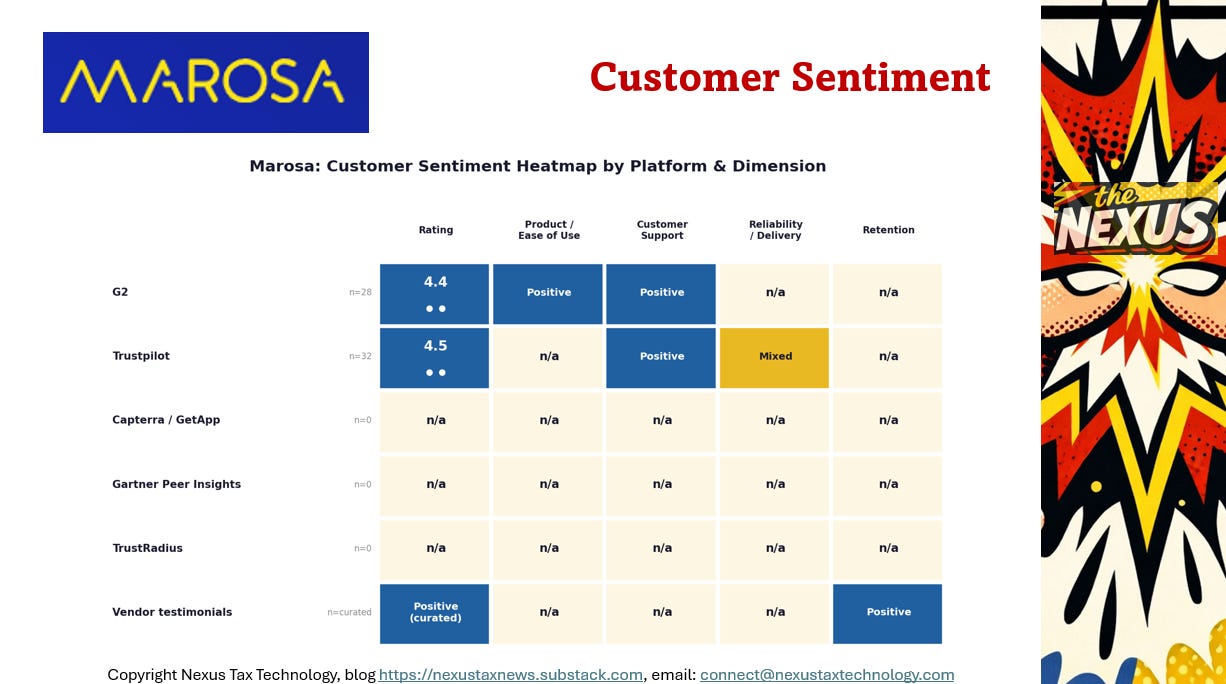
G2 (4.4/5, ~28 reviews): reliability, professionalism, and a “well thought out” tech stack are the recurring themes.
Trustpilot (4.5/5, 32 reviews): strongly positive overall, with a sharp negative minority flagging delivery timeliness on new VAT setups.
Capterra, Gartner Peer Insights, TrustRadius: no presence found — a narrower footprint than category leaders.
Glassdoor (3.6/5, 20 reviews): career growth (4.1) and culture (3.8) score well ahead of work-life balance (2.7) and comp (3.0) — classic scale-up strain.
Sentiment confirms the rubric: strong on substance, thinner on delivery bandwidth. Get delivery-timeline and escalation commitments in writing before you sign anything beyond the core subscription.
IF YOU’RE BUILDING OR BUYING INDIRECT TAX CAPABILITY — HERE’S THE READ
For buyers
If you’re a Medium or Large B2B goods or services business centralising EU/UK VAT across multiple entities — especially if you’re newly exposed to France, Poland, Spain or Germany’s e-invoicing mandates — Marosa belongs on your shortlist. If you need one platform to cover US sales tax alongside VAT, look elsewhere. If you’re a small, self-serve buyer wanting transparent pricing and a same-day start, the sales-assisted-only funnel will frustrate you. Whatever your size, get the ISO 27001 certificate, an SLA, and a delivery-capacity commitment in writing before signing anything beyond the core subscription.
For prospective employees
Good move for tax-technology and product specialists: genuine AI investment (four working tools, not a slide) means real, current problems to work on.
Attractive if you like fast-moving, services-heavy environments: Praxity’s alliance channel and fresh PE capital point to real growth, not just talk.
Go in with eyes open on workload: Glassdoor’s work-life-balance (2.7) and comp (3.0) scores trail its culture and career scores — ask directly about hours and pay before joining.
No RepVue data exists to size up the sales org — if you’re evaluating a sales role, that’s a gap worth probing directly in interviews, not assuming away.


A selection of of opportunities to connect in person and interact online over the next few weeks
AUGUST 2026
The New Indirect Tax Technologist: A Skillset and Team Structure for the AI Era (Webinar)
Fonoa | 11 August 2026, 4:00pm CEST / 10:00am ET | Online
Tax leaders from NVIDIA, KPMG, and Fonoa discuss how to structure, hire, and upskill an indirect tax team that gets real value from AI — covering the emerging skillset and team design questions facing tax functions in the AI era.
SEPTEMBER 2026
E-Invoicing Compliance & Tax Technology Summit (Conference)
Tax Technology Summit | 2 September 2026 | Dubai, UAE
A summit convening global tax and finance leaders in Dubai to examine the next chapter of digital tax administration in the Middle East and GCC region, covering e-invoicing implementation, AI-driven compliance, and what Phase 1 live reporting means in practice.
Audits & Appeals Seminar 2026 (Seminar)
TEI — Tax Executives Institute | 8–10 September 2026 | TBC
A deep-dive seminar equipping in-house tax professionals with the tools and strategies to navigate IRS audits and appeals in an environment where tax administration has shifted significantly — covering preparation, documentation, and the appeals process.
Shared Services & Outsourcing Week 2026 — Autumn (Conference)
SSON — Shared Services & Outsourcing Network | 14–17 September 2026 | San Diego, CA
SSON’s autumn flagship conference covering finance, tax, HR, and IT shared services transformation, with a focus on AI adoption, automation, and the future of the GBS operating model.
Avalara CRUSH 2026 (Conference)
Avalara | 22–24 September 2026 | Fort Lauderdale, FL
Avalara’s premier annual conference returns as agentic AI reshapes tax and compliance. A key gathering for finance, tax, and technology professionals exploring the future of automated, AI-powered global tax compliance — with product deep-dives, partner sessions, and peer networking.
E-Invoicing Exchange Summit 2026 (Conference)
E-Invoicing Exchange | 30 September – 2 October 2026 | Hotel MOA Berlin, Berlin, Germany
The leading independent e-invoicing industry event returns to Berlin, bringing together enterprises, tax authorities, and technology providers to share insights on cross-border interoperability, regulatory readiness, and the growing impact of AI on e-invoicing and tax processes.
*any organisers or events I’ve missed? please let me know.

A curated selection of blogs, white-papers and on demand content published by multiple organisartions across the landscape, organised into a themed learning path.
AUGUST 2026
Market Intelligence, AI, Agentic Governance & Audit Readiness
August blends the strategic landscape — where the market stands, how AI is actually being deployed, and the emerging governance question that dominated Compliance Connect London — with a strong practical thread on audit readiness. Each week contains a mix of strategy, AI, indirect tax, and operational content so no single theme monopolises a week.
Week 1 · 4–8 August
Setting the Scene: Market Data, Regulatory Context & the AI Inflection Point
01📖 6 Insights from the 2026 Corporate Tax Technology Report Thomson Reuters / TEI 10–12 min
02📖 2026 Indirect Tax TrendsVertex Inc. 8–10 min
03📖 The Future of Tax: Connected Modeling and an AI-Enabled Tax Function KPMG 8–10 min
04📖 Sovos TaxScapes Q1 2026: Regulatory Changes in the Last 90 Days Sovos 10–12 min
05🎥Compliance Connect London 2026 — On-Demand Sessions Thomson Reuters / Pagero 90–120 min
06🎥 Sovos TaxScapes July 2026: What’s Changing in Indirect Tax — US and Global Sovos 45–60 min
Week total: 4 articles + 2 webinars · ~171–224 min (~2.5–3.5 hrs)
Week 2 · 11–15 August
AI Strategy, Agentic Governance & the Vendor Landscape
07📖 The Majority of CFOs Require Human Oversight of Agentic AI: 4 Governance Frameworks Anrok 12–15 min
08📖 AI Tools for Tax Professionals: Automate Smarter, Not Harder Sphere 10–12 min
09📖 AI for Indirect Tax: How Human-AI Collaboration Improves Compliance Fonoa 10–12 min
10📖 Best Sales Tax Software for SaaS Companies: 2026 Guide Kintsugi 12–15 min
11📖 5 Key Indirect Tax Trends from SYNAPSE 2026 Fonoa 10–12 min
12🎥 Beyond the Return: How AI and Automation Are Reshaping Tax Preparation Wolters Kluwer / CCH 50–60 min
Week total: 5 articles + 1 webinar · ~104–126 min (~1.75–2 hrs)
Week 3 · 18–22 August
Audit Readiness, Organisational Maturity & the Strategic Tax Function
13📖 Ready Before the Notice: A Sales Tax & VAT Audit Playbook Anrok / KPMG 20–25 min
14📖 Multi-State Tax Complexity: What Tax Teams Need to Know Wolters Kluwer / CCH 8–10 min
15📖 Beyond Compliance: How Tax Professionals Are Becoming Strategic Advisors Wolters Kluwer / CCH 8–10 min
16📖 Survive or Thrive? 2026 Will Test Tax Teams’ Limits Wolters Kluwer / CCH 6–8 min
17📖 Transforming Indirect Tax: 5 Insights from the 7th Annual VAT Management Summit Fonoa 10–12 min
18🎥From VAT Reporting to Real-Time Control: The New Era of VAT Compliance Sovos 45–60 min
Week total: 5 articles + 1 webinar · ~97–125 min (~1.5–2 hrs)
Week 4 · 25–29 August
Platform Strategy, the Vendor Market & the Indirect Tax Architecture Decision
19📖 Vertex Announces Strategic Investment in Kintsugi: Market Signal Vertex / Kintsugi 6–8 min
20📖 Tax Tech Strategy: Integrate Technology for Compliance Fonoa 10–12 min
21📖 Indirect Tax Transformation: Navigating Change, Embracing Technology Thomson Reuters 10–12 min
22📖 8 Best Cross-Border VAT Compliance Software: 2026 Guide Kintsugi 12–15 min
23🎥 Embracing the Future of Tax Compliance with AI Avalara 45–60 min
Week total: 4 articles + 1 webinar · ~83–107 min (~1.5 hrs)
August total: 18 articles + 5 webinars = 23 resources · ~455–582 min (~7.5–9.5 hrs)
*any cool content I’ve missed? please let me know.

A selection of open roles across tax tech vendors and tax advisory/consulting businesses who are involved in tax technology.
In house roles are provided courtesy of the smart people at https://taxjobs.ai
Use the column headers to sort, or the search function and don’t forget to navigate all pages!
*I do this using an AI agent and due to the volume, I don’t check every link, so please let me know if any of these don’t work or have disappeared when you follow them.