
Compliance Isn’t Coming. It’s Already Being Sold.
April 2029 feels distant until you notice how loud the market already is.
HMRC confirmed Peppol as the UK’s e-invoicing backbone on 23 June 2026. Within days, dozens of vendors had a blog post ready. Most of them said the same thing.
Here’s the split that actually matters: who’s shipped something real in the UK, and who’s just SEO-ing the mandate. Twenty-one organisations we tracked have said something UK-specific. A handful have said something that would survive an RFP.
The Numbers Behind the Noise
Start with the one number HMRC actually counted: 342 consultation responses between February and May 2025 — 259 UK-only, 203 businesses (141 of them sub-250-employee SMEs, 40 large enterprises), the rest advisers and trade bodies.
Everything after that is vendor noise, and the noise has a shape. Across six cohorts — tax engines, e-invoicing specialists, VAT-tech challengers, SME accounting platforms, Big 4, professional bodies — 21 organisations have published genuinely UK-specific content since Budget 2025: four tax engines, four e-invoicing specialists, four challenger firms, three accounting platforms, three of the Big 4, three associations.
Now the gap. Zero of the three major ERP vendors — SAP, Microsoft, Oracle/NetSuite — has made a first-party UK statement. One of the Big 4 (PwC) has published nothing UK-specific we could find. Biggest balance sheets, quietest press office. Remember that when a systems integrator tells you your ERP vendor “has it covered.”
And the number that should worry HMRC more than any of the above: roughly 40% of UK businesses don’t know this mandate exists, and over 90% have seen zero direct communication from HMRC about it. Billentis pegs global e-invoice penetration at just 29% of roughly 300 billion B2B invoices expected in 2026. Twenty-one vendors publishing at full volume, into a market where nine in ten businesses haven’t had the conversation yet.
Tax Engines: Vertex, Avalara, Pagero/Thomson Reuters, Sovos
Vertex has UK content — a “why VAT businesses must prepare” piece, a steady drip of regulatory alerts — that reads as e-invoicing bolted onto the existing VAT Compliance module: reconciliation, status tracking, the usual. Avalara’s play is standards alignment, EN 16931 folded into a pan-European tracker rather than owned as a UK story, though it does sit as one of the certified providers wired into Microsoft Dynamics 365’s Peppol connectivity. Pagero — now folded entirely into Thomson Reuters as ONESOURCE Pagero — carries the NHS’s invoicing modernisation as a live reference case, plus accreditation across every Peppol jurisdiction. Sovos was fastest off the blocks with content, but its real substance is structural: the embedded engine inside QuickBooks/Intuit’s UK product, paired technically with Tungsten Automation on tax-plus-AP.
Signal: two of four are real, two are commentary. Pagero/Thomson Reuters has shipped, large-scale UK infrastructure (the NHS deployment); Sovos is functionally embedded inside a live UK product most of the market already uses. Vertex and Avalara have said the mandate is important — accurate, and not a position.
E-Invoicing Specialists: Basware, Tungsten Automation, Tradeshift, Comarch
Basware is an accredited Peppol access point that’s actually built the Peppol Invoice Response Message — real protocol engineering — and has been buying AP-automation capability (Redmap, AP Matching) to round out the stack. Tungsten leans on country-coverage breadth and its Sovos tie-up. Comarch has simply out-published everyone, with a dedicated UK page tracking the consultation, the Budget and the Peppol confirmation in turn. Tradeshift is named as a direct participant in the UK eInvoicing Advocacy Lab.
Signal: Tradeshift wins this cohort outright — a seat in the room writing the rules beats every competitor’s forward-looking blog post, and it’s the most substantive “response” available to anyone before Budget 2026 drops the actual spec. Basware backs its claims with genuine engineering; Tungsten and Comarch are competent but undifferentiated.
The Challengers:
Fonoa is a certified OpenPeppol member, accredited to run both a Peppol Access Point and a Service Metadata Publisher, with a dedicated UK guide. Marosa VAT and Fintua have both stayed current on the consultation and Budget cycle, with Fintua folding e-invoicing into a broader VAT-compliance-plus-recovery-plus-payments suite. VATCalc — built by ex-Avalara executive Richard Asquith — offers a live product (e-invoicing reconciled against VAT returns across 30+ countries) and a sharp independent read in the landscape: its framing of the Peppol decision as an “efficiency drive” rather than a tax-gap play is genuinely contrarian.
Signal: only one clears the infrastructure bar. Fonoa has certified, shipped Peppol capability — real signal, from a company most of the market still files under “API tax automation.” VATCalc’s signal is real but different in kind: independent analytical credibility rather than proven UK deployment — we found no UK-specific certification or reference case to match Fonoa’s, so treat its commentary as a reason to watch the firm, not yet a reason to shortlist it on infrastructure.
ERP and Accounting Platforms
The SME tier is talking. Xero has genuine first-mover bragging rights — live UK eInvoicing since 2023, Peppol receiving already switched on. Sage has a dedicated UK page, though Sage 50 and Sage 200 have zero native Peppol support and lean entirely on third-party bolt-ons. QuickBooks/Intuit took the buy-not-build route outright, wiring in Sovos.
The enterprise tier is silent. SAP’s Document and Reporting Compliance covers six European countries — not the UK; the only UK-specific SAP content anywhere is a UKISUG user-group event, not SAP itself talking. Microsoft’s Business Central documentation lists native Peppol support for six countries — not the UK — leaving the UK conversation to ISV partner Continia. Oracle/NetSuite offers generic Peppol capability and no UK statement at all.
Signal: real, and the sharpest finding in this piece. The SME platforms — a fraction of the market cap of the ERP giants — are the ones actually talking to UK customers by name. If you’re running SAP, Dynamics or NetSuite, stop waiting for your platform vendor to lead here; nobody at those three has said a word about the UK specifically.
Big 4 and Accounting Firms
KPMG has the most developed UK content, pairing its Budget 2025 analysis with HMRC’s own SME-awareness data. EY flagged the original consultation with a specific alert. Deloitte has a standalone blog making the early-preparation case. PwC: nothing UK-specific found.
Signal: KPMG is the one genuine value-add in this cohort — primary data, not restated policy. PwC’s silence, given its UK tax-advisory footprint, is loud enough to flag to clients assuming blanket Big 4 coverage of this topic.
Associations: ICAEW, CIOT, ATT
All three filed real consultation responses, and together they’re the only cohort here arguing for smaller or slower. ICAEW wanted voluntary-first, mandation held to 2030 at the earliest — overruled on timing. CIOT wants one flexible UK standard and phasing by size. ATT went furthest with actual numbers: a VAT-threshold exemption, a de minimis carve-out for low-volume B2B/B2G trade.
Signal: ATT’s is the most legislatable position on the table — specific thresholds a policymaker could act on. ICAEW’s is the most fully worked through, even though government didn’t take it.
HMRC Itself
Twelve weeks of consultation, a considered no to the voluntary-first path ICAEW and ATT pushed for, and a decentralised four-corner model chosen partly to dodge the clearance friction that’s caused real pain elsewhere in Europe. Budget 2026 carries the real weight: syntaxes, phasing, enforcement, legacy EDI.
Signal: HMRC’s own awareness gap — 40% unaware, 90%+ never contacted — is the one problem on this list HMRC hasn’t visibly fixed, sitting awkwardly next to a vendor market already at full volume.
Three Moves for Sophisticated Buyers
Stop accepting certification as a proxy for readiness. “EN 16931-ready” and “Peppol-certified” are table stakes, not differentiators. Ask for a shipped UK or Ireland deployment at real volume — Thomson Reuters/Pagero’s NHS work is the bar.
If you’re on SAP, Dynamics 365 or NetSuite, run your access-point selection now — independently of your ERP roadmap. None of the three has a first-party UK commitment. Connectivity today comes from bolted-on partners. Waiting for native support risks missing the 2027–28 pilot window entirely.
Contract against the Budget 2026 spec, not today’s generic pitch. Lock vendors into delivering PINT UK/Peppol BIS Billing 3.0 support within 90–120 days of publication, with access-point pricing defined now — platform fee, per-document, per-connection. Negotiate that clause today. Don’t renegotiate it from weakness in 2028.
Sources:
vatcalc.com — UK April 2029 Peppol confirmed B2B e-invoicing
The Invoicing Hub — Billentis 2026 report “Riding the Tornado”
Tungsten Automation — United Kingdom e-Invoicing Compliance Updates
UKISUG — Mandatory UK E-invoicing: What it means for SAP and Finance Teams
Microsoft Learn — Supported electronic invoicing countries and regions
SimplyDynamics — Continia eDocuments Countdown: Ireland and UK
Chartered Institute of Taxation — E-invoicing announcement is big news for VAT registered businesses
Association of Taxation Technicians — E-invoicing 2029 start date response
Now staying in the UK we’ll take a look at home-grown SMB VAT challenger LOVAT
⭐ Vendor Spotlight: LOVAT
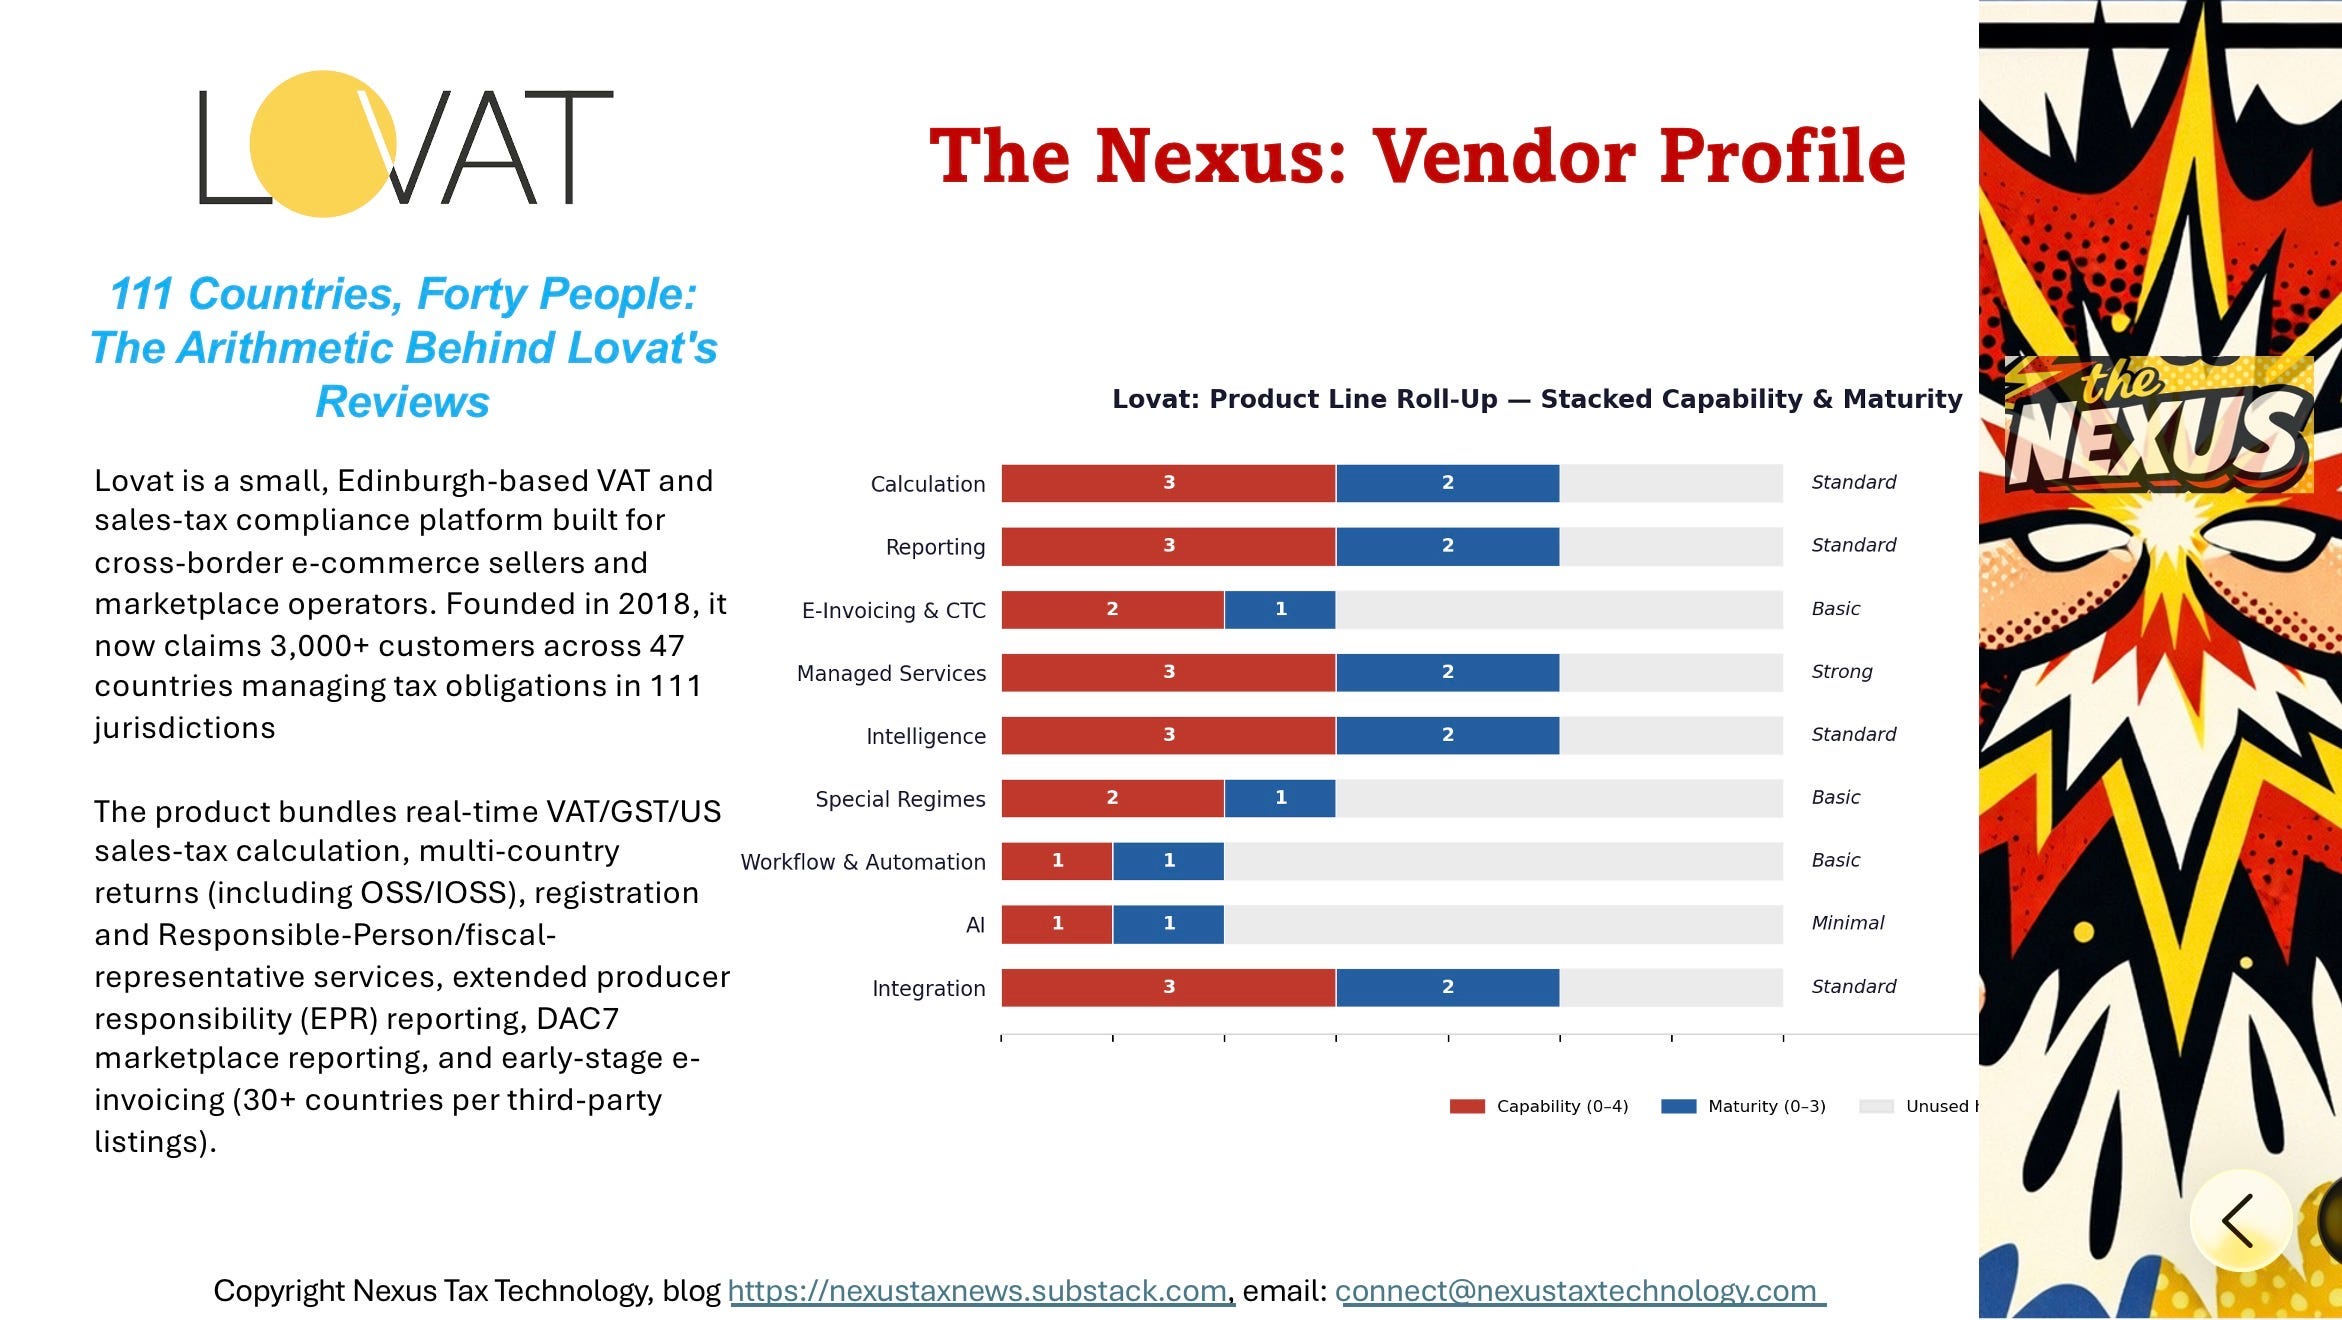
111 Countries, Forty People: The Arithmetic Behind Lovat’s Reviews
Every e-commerce seller eventually hits the same wall: VAT registration somewhere they barely sell, an EPR obligation they didn’t know existed, a DAC7 form with a deadline attached. Lovat has built a genuinely clever, cheap answer to that wall — and a ~40-person team is now the whole reason to read the fine print before you rely on it.
WHAT IT ACTUALLY IS
Lovat is an Edinburgh-built VAT/GST and US sales-tax platform for cross-border e-commerce sellers and marketplace operators: real-time Calculation and Reporting across 111 countries and all 50 US states, wrapped in Managed Services (registration, Responsible Person/fiscal representation, EPR, DAC7 marketplace reporting). Integration is entirely e-commerce-native — Amazon, Shopify, eBay, Etsy, WooCommerce, Magento, AliExpress, Stripe, PayPal, Xero, plus a REST API — with no SAP, Oracle, or Dynamics connector anywhere. Center of gravity: small-business, marketplace-first, price-led, not enterprise.
Scale: ~40–42 employees serving 3,000+ customers across 47 countries, on an estimated ~$3.0–4.0M ARR (no disclosed revenue). Longlist material for solo and small-team digital sellers — not for anyone running tax through an ERP.
WHERE IT BEATS THE MARKET BASELINE
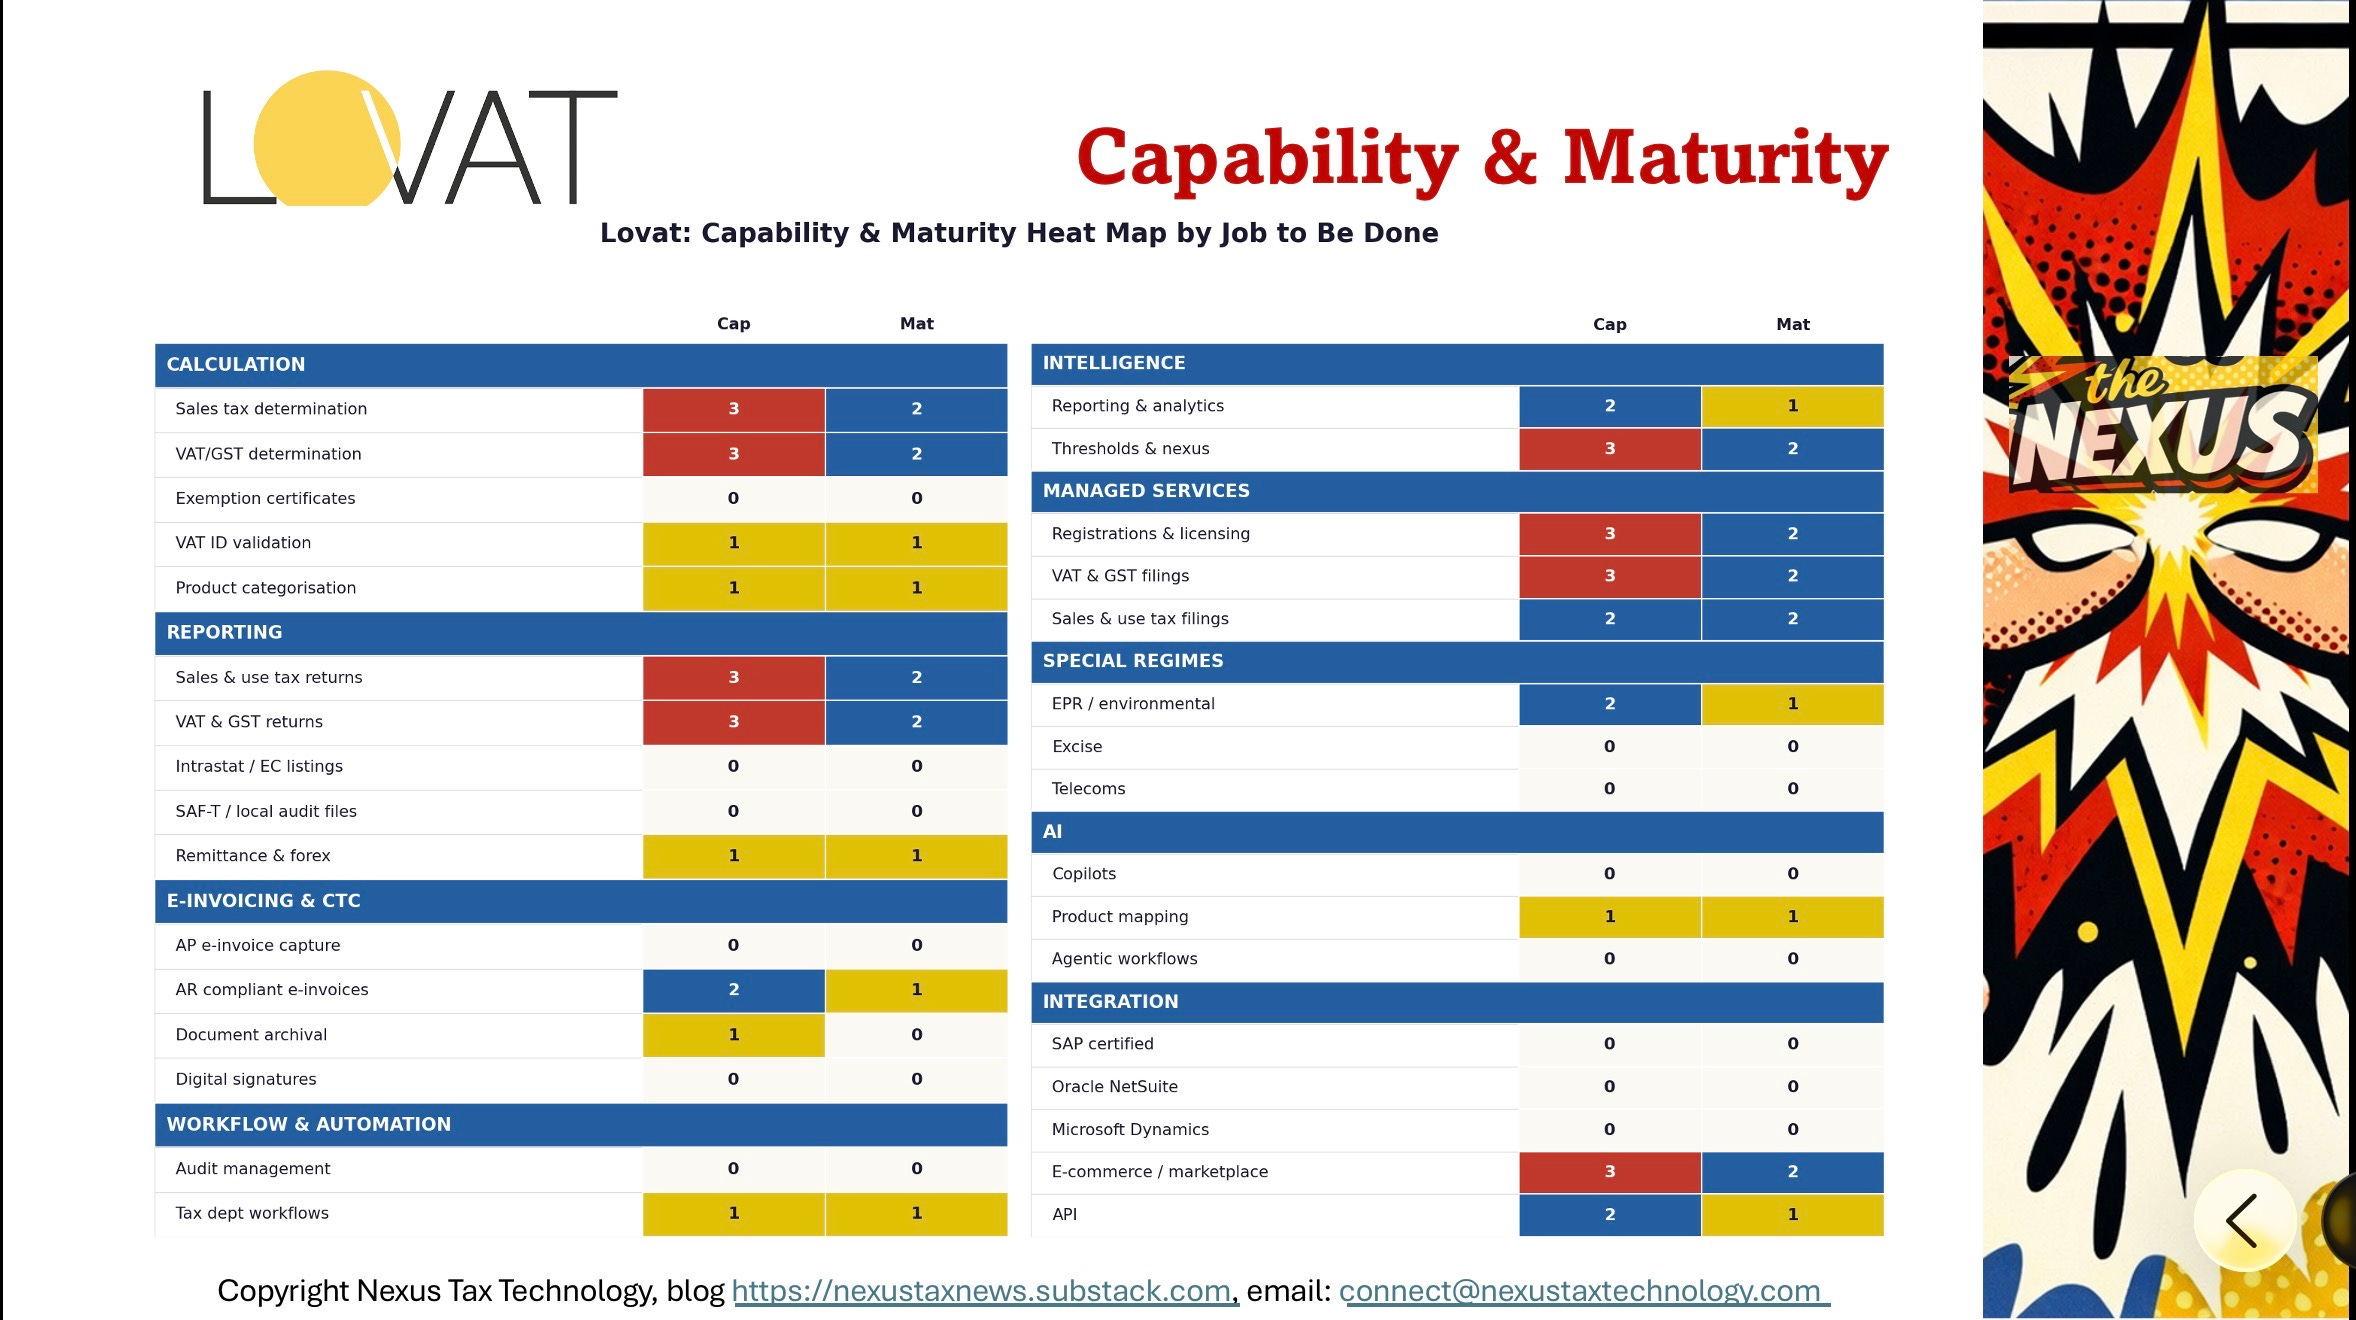
Against the indirect tax tech baseline, Lovat wins on breadth-per-dollar and onboarding friction, not depth. Its free nexus/threshold-monitoring tier is a smart acquisition wedge most vendors gate behind a paid plan. EPR is a first-class, actively marketed line — a sharp bet given how many sellers are newly exposed to packaging/WEEE/battery rules — and DAC7 shipped ahead of the compliance deadline, not behind it. Below baseline: no SAF-T or Intrastat at all, “30+ country” e-invoicing that’s a listing claim rather than audited depth, and a pricing-transparency complaint that recurs across reviews.
PORTFOLIO ANALYSIS
No M&A story here, and that’s the point: Lovat grew its line-up (EPR, DAC7, e-invoicing) organically, riding regulatory scope-creep among its base rather than buying geography or credibility. Calculation and Reporting are the estimated revenue core (~60% combined); Managed Services adds ~25% and is growing — and it’s that services layer, not the software, where operational strain shows up. Read this as a tight, single-codebase small-business product, not a platform assembled from acquisitions — which also means it was never built to absorb enterprise-scale complexity.
BUSINESS MODEL AND SIZE BAND FIT
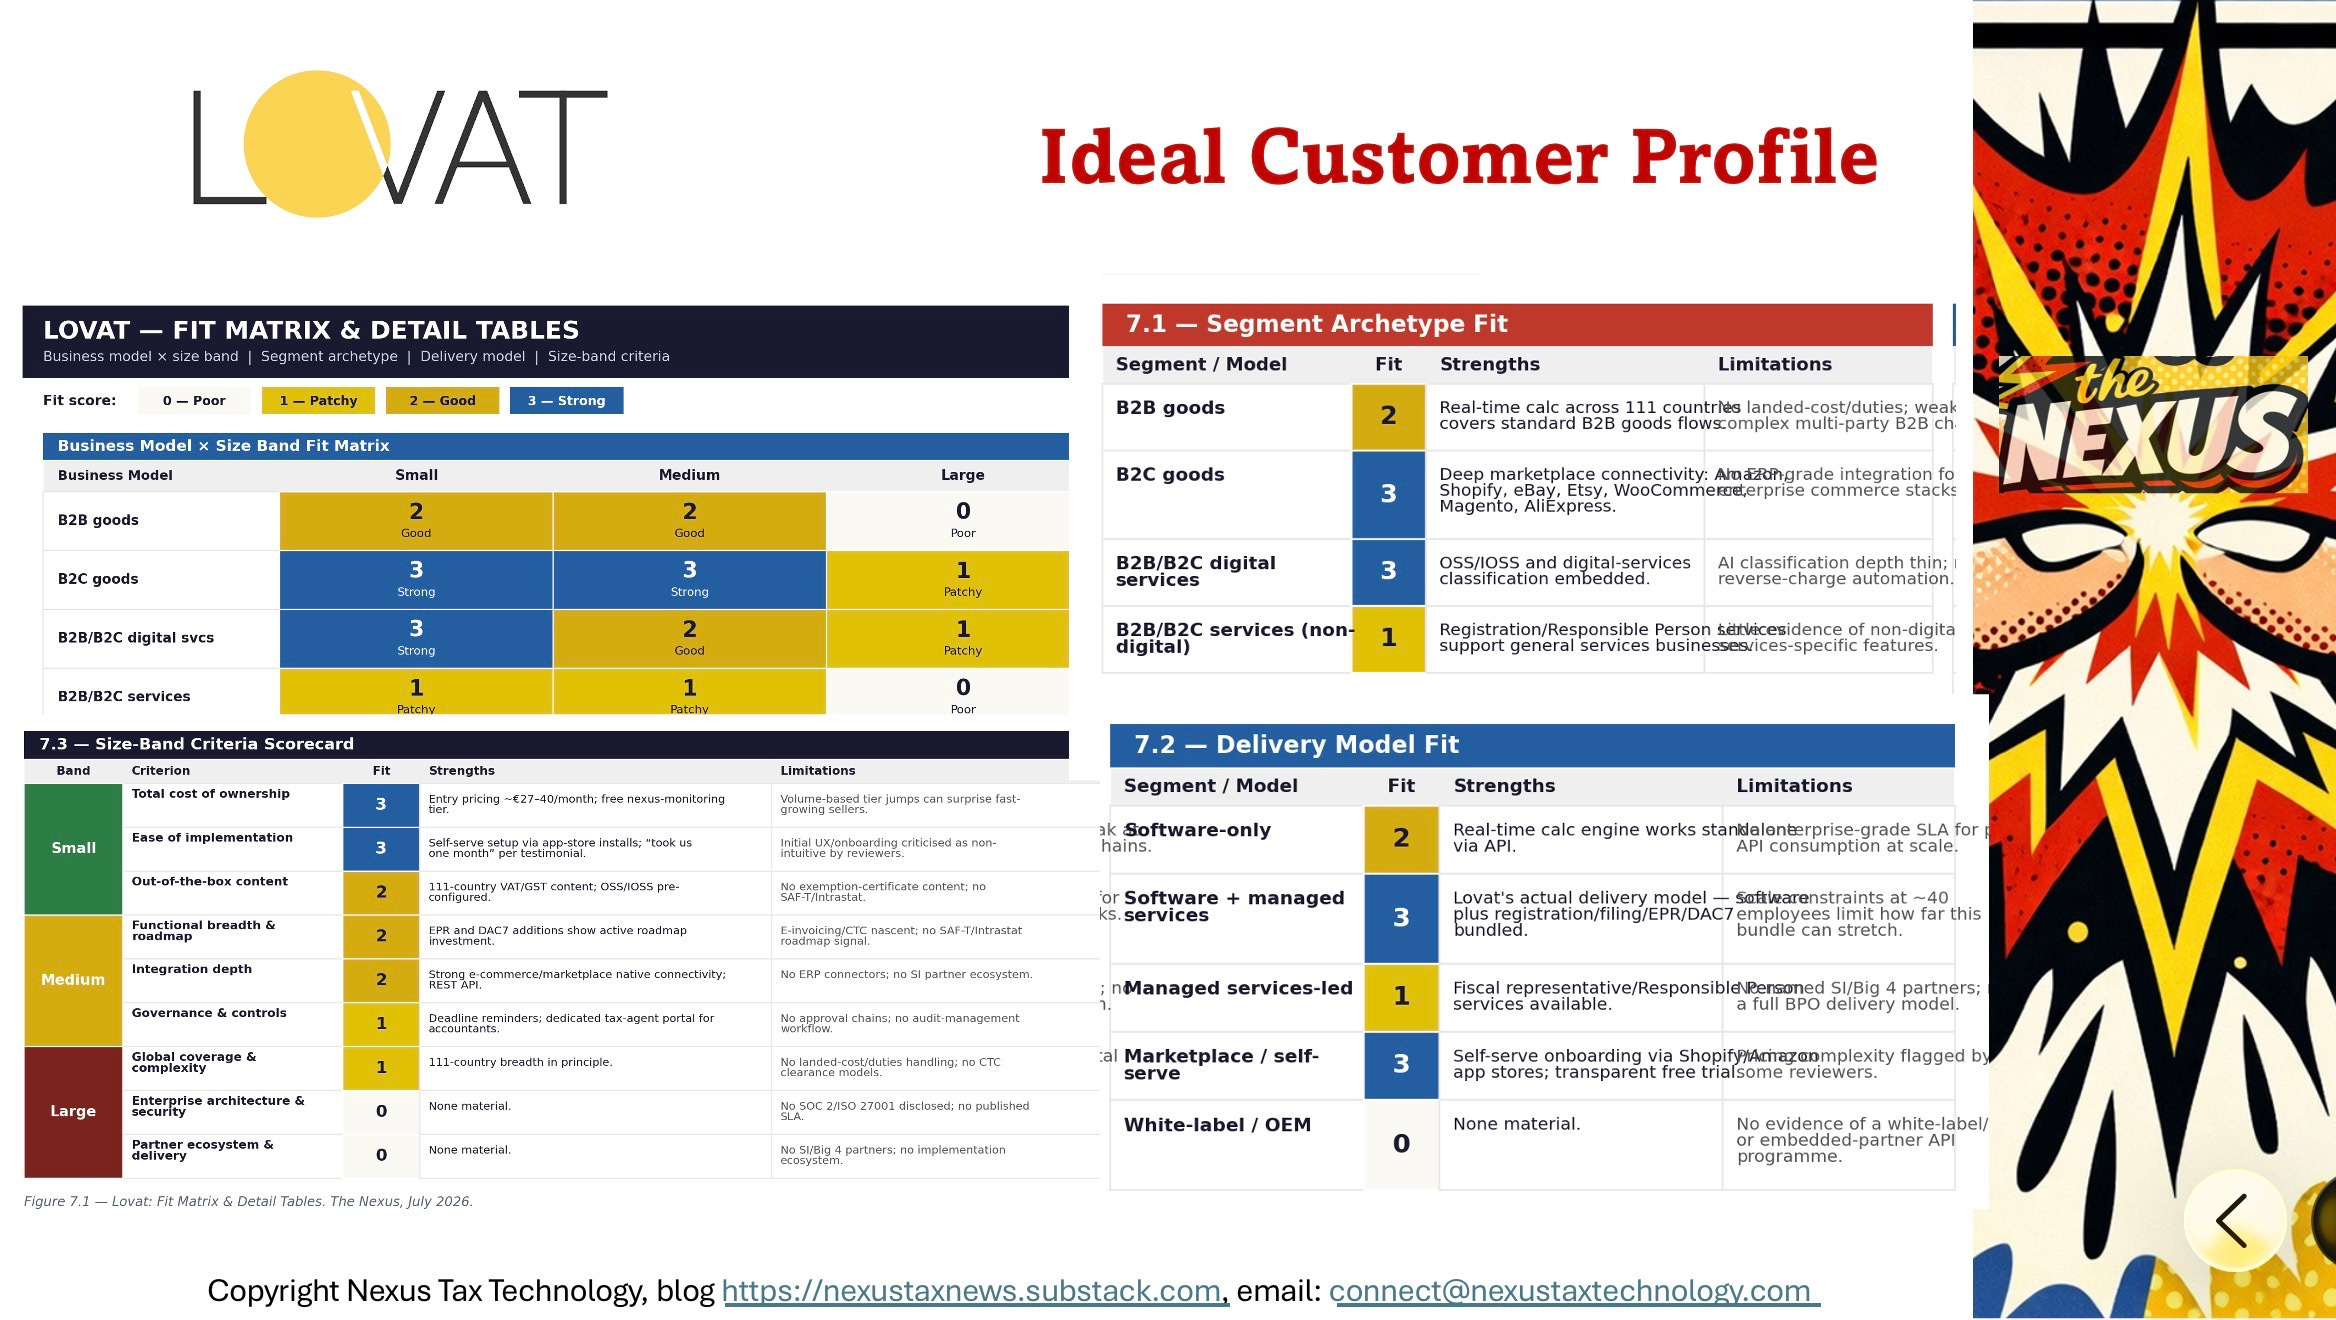
Business model fit:
● B2B goods — 2, Good fit (Small/Medium), 0, Poor fit (Large): covers standard flows, but no landed-cost or duties handling for complex chains.
● B2C goods — 3, Strong fit (Small/Medium), 1, Patchy (Large): the core use case, built around marketplace-native integration.
● B2B/B2C digital services — 3, Strong fit (Small): OSS/IOSS and digital-services classification are embedded and it shows.
● B2B/B2C services (non-digital) — 1, Patchy fit throughout: registration/Responsible Person help, but little is purpose-built here.
Size band fit:
● Small — 3, Strong fit: entry pricing from ~€27–40/month, a free tier, self-serve setup reviewers clock at about a month.
● Medium — 2, Good fit: works, but pricing-transparency and manual-upload friction bite as complexity grows.
● Large — 0, Poor fit: no ERP integration, no disclosed security certification, no SI ecosystem — structural, not a matter of degree.
CUSTOMER AND EMPLOYEE SENTIMENT
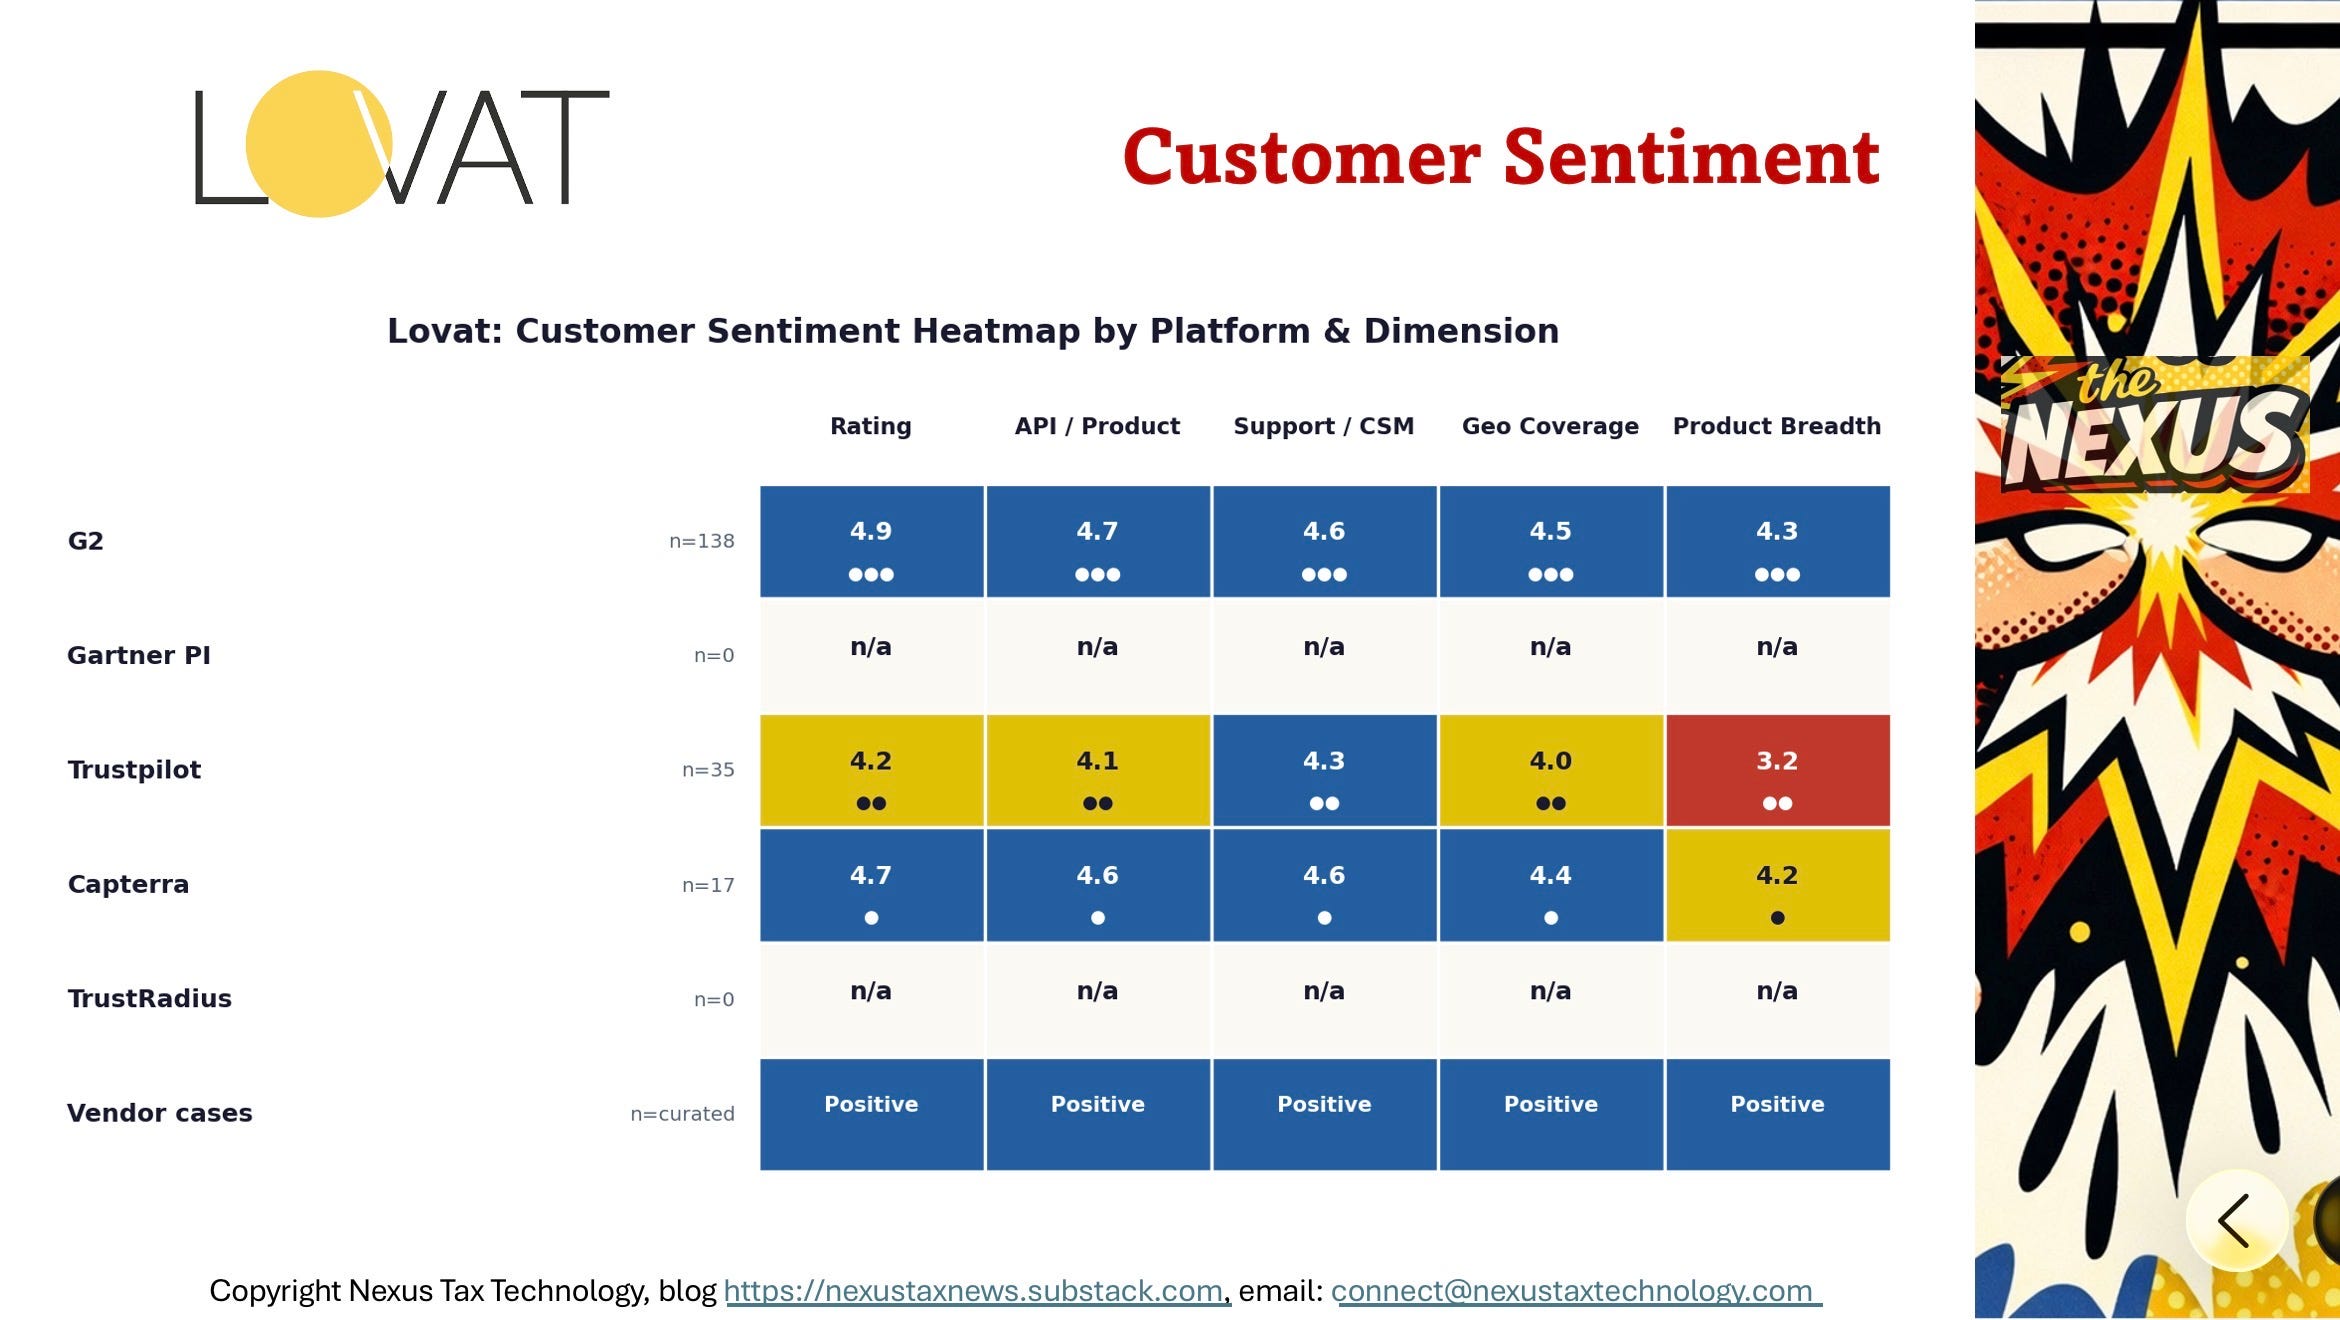
Sentiment is strikingly consistent across every platform that has one: strong on rating and ease of use, with pricing transparency the one dimension that reliably drags scores down.
● G2: 4.9/5 (138 reviews) — automation and filing accuracy praised; interface complexity is the recurring gripe.
● Capterra/GetApp: ~4.7 (17 reviews) — dashboard/threshold tracking and support reviewers call out by name.
● Trustpilot: 4.2/5 (35 reviews), sharply bimodal — 86% five-star, but an 11% one-star tail on multi-month registration delays and pricing mismatches.
● Glassdoor/RepVue/Indeed: no usable data (the one Glassdoor “Lovat” listing is an unrelated company). LinkedIn shows ~41–42 employees, hiring concentrated in support/tax-ops.
Operator read: a ~40-person team supporting 3,000+ customers across 111 countries is thin bench depth by simple arithmetic — and the Trustpilot outliers look exactly like that strain showing through.
IF YOU’RE X, DO Y
If you’re a small e-commerce seller on Amazon, Shopify, eBay, Etsy, or WooCommerce needing EU/UK VAT registration, OSS/IOSS, and threshold monitoring in one cheap dashboard — shortlist by default. Same answer if you’re a marketplace operator needing DAC7 bundled with core VAT. If you’re Medium-size and multi-country, it still works, but get registration turnaround and total pricing in writing first. If you’re Large or multinational and expect ERP-grade determination, a security certification, or a formal SLA — don’t shortlist this one; no packaging of the current product solves those gaps.
For prospective employees:
● Support and domain specialists likely thrive here — it’s doing real, visible work per reviewer testimony.
● No usable Glassdoor/RepVue/Indeed signal on culture or leadership — a genuine blind spot, not a clean bill of health.
● At ~40 people covering 111 countries, expect broad generalist scope over narrow specialisation.
Want the full 27 page analyst report?

A selection of of opportunities to connect in person and interact online over the next few weeks
JULY 2026
NAEA Tax Summit 2026 (Conference) | National Association of Enrolled Agents | 27–29 July 2026 | New Orleans Marriott, New Orleans, LA
NAEA’s flagship in-person event for tax practitioners, including a dedicated Practice Management Bootcamp track covering the tools, workflows, and automation strategies powering efficient firms today.
Prompt Engineering for Tax Teams: Hands-On AI Lab (Virtual Workshop) | TEI — Tax Executives Institute | 29 July 2026 | Virtual
A hands-on session for in-house tax professionals on applying prompt engineering techniques directly to tax workflows — practical AI skills rather than theory.
AUGUST 2026
FTA Technology Conference and Expo 2026 (Conference) | Federation of Tax Administrators | 2–5 August 2026 | St. Louis Union Station, St. Louis, MO
The premier gathering for state tax administrators, software vendors, and compliance teams — a key venue for indirect tax automation vendors engaging directly with government decision-makers on emerging requirements.
US International Tax Course 2026 (Course) | TEI — Tax Executives Institute | 3–7 August 2026 | Seattle, WA
TEI’s intensive week-long course for in-house tax professionals covering the full spectrum of US international tax — from Subpart F and GILTI through FDII, BEAT, and transfer pricing — with substantial CPE credit available.
*any organisers or events I’ve missed? please let me know.

A curated selection of blogs, white-papers and on demand content published by multiple organisartions across the landscape, organised into a themed learning path.
MONTH TWO · JULY 2026
E-Invoicing, CTC & the Live Mandate Landscape
Belgium is in full enforcement. France’s September 2026 deadline is six weeks away. Poland’s KSeF soft-landing period is closing. Norway has just accelerated its mandatory timeline. Brazil’s dual-VAT transition is live. Comarch, Basware, Marosa, Innovate Tax, and Sovos are the specialist lenses for this month — alongside Fonoa and Vertex for the platform and maturity dimensions.
Week 1 · 6–10 July
The Global CTC Landscape: What 80+ Live Mandates Actually Look Like
📖Continuous Transaction Controls: The Future of Compliance Sovos 12–15 min
📖Streamline the Future #6: Reporting Built for Global E-Invoicing Operations Comarch 8–10 min
📖2025 in Review: 5 Trends That Defined the Indirect Tax Industry Innovate Tax 8–10 min
Week total: 3 articles · ~28–35 min
Week 2 · 13–17 July
ViDA, Belgium & the European Mandate Wave
Basware’s recently confirmed accreditation as a certified French PDP (Plateforme de Dématérialisation Partenaire) makes it one of the most credible voices on France’s September 2026 mandate. The Comarch / Forrester webinar from January 2026 remains the most authoritative external analysis of the global e-invoicing technology landscape — covering GenAI, agentic AI, Peppol, and the 2026–2027 mandate timeline in 60 minutes.
📖 What is ViDA? VAT in the Digital Age Initiative Q&A Pagero (Thomson Reuters) 12–15 min
📖5 Things We Can Learn from Belgium’s 2026 E-Invoicing Mandate Innovate Tax 8–10 min
🎥E-Invoicing Trends and Obligations: 2026 and Beyond (feat. Forrester) Comarch / Forrester 60 min
Week total: 2 articles + 1 webinar · ~80–85 min
Week 3 · 20–24 July
Emerging Markets & Platform Architecture: Brazil, Norway & Building for Scale
Brazil’s 2026 CBS/IBS tax reform is the most structurally significant emerging market e-invoicing development of the year — Fonoa’s guide is the most accessible and detailed available for non-specialists. Marosa’s country monitoring brings a European VAT compliance partner’s practical lens on the mandates moving fastest right now (Norway’s just-announced acceleration, Spain’s reactivated B2B requirement). Vertex’s platform consolidation argument provides the architectural counterpoint.
📖Brazil 2026 Tax Reform: Key E-Invoicing Changes Fonoa 10–12 min
📖E-Invoicing in Norway and Latest European VAT Updates Marosa VAT 8–10 min
📖Leading the Charge: E-Invoicing as the Cornerstone of Future Compliance Vertex Inc. 10–12 min
Week total: 3 articles · ~28–34 min
Week 4 · 27–31 July
The Buyer’s Market: Evaluating VAT & E-Invoicing Tools Across the Vendor Spectrum
This week deliberately introduces the buyer’s perspective — how do you navigate a market that now runs from $49/month Quaderno for SaaS B2C through to Comarch, EDICOM, and Basware serving Fortune 500 multinationals? Kintsugi’s cross-border VAT guide maps the mid-market options clearly. The Sovos webinar provides the live regulatory update that anchors the month. Avalara’s AI webinar closes the loop on how automation is being embedded into compliance workflows in 2026.
📖8 Best Cross-Border VAT Compliance Software: 2026 Guide Kintsugi 12–15 min
🎥VAT Snapshot: From Poland to the UAE — Preparing for 2026 Mandates Sovos 45–60 min
🎥Embracing the Future of Tax Compliance with AI Avalara 45–60 min
Week total: 1 article + 2 webinars · ~102–135 min
Month Two total: 9 articles + 3 webinars · ~238–289 min
*any cool content I’ve missed? please let me know.

A selection of open roles across tax tech vendors and tax advisory/consulting businesses who are involved in tax technology.
Use the column headers to sort, or the search function and don’t forget to navigate all pages!
*I do this using an AI agent and due to the volume, I don’t check every link, so please let me know if any of these don’t work or have disappeared when you follow them.
✌ Last thoughts
Thanks again for reading! If you have any feedback, suggestions, want to contribute, share gossip or would like to work together in any way, email me here or hit the button below! And if you haven’t already, please subscribe to get The Nexus each and every Friday!