
TL;DR Various market updates, customer vendor selection tool introduced, 114 Jobs, 9 events, 4:31 hours of learning and Vendor showdown: Part 2 (Indirect Tax Platforms)
❤
Welcome to the 6th edition of the Nexus and the 2nd half of the vendor comparison report. I think you’ll find this interesting as it goes beyond what’s explicitly discussed around products and looks at the overall proposition and how it fits certain sizes and types of business models, as well as bringing in external feedback from customers and internal feedback from employees (sad employees = sad customers).
Outside of that we had a few interesting announcements, one from Vertex regarding their Acquisition of Brinta which plugs an obvious hole in their CTC coverage in LATAM, which is important for their largely US HQ’d customer base.
The other from Thomson Reuters (who were probably feeling a little left out after all the others announced their AI capabilities) regarding a new Indirect compliance AI feature and then some updates to Amazon’s VAT capabilities for sellers
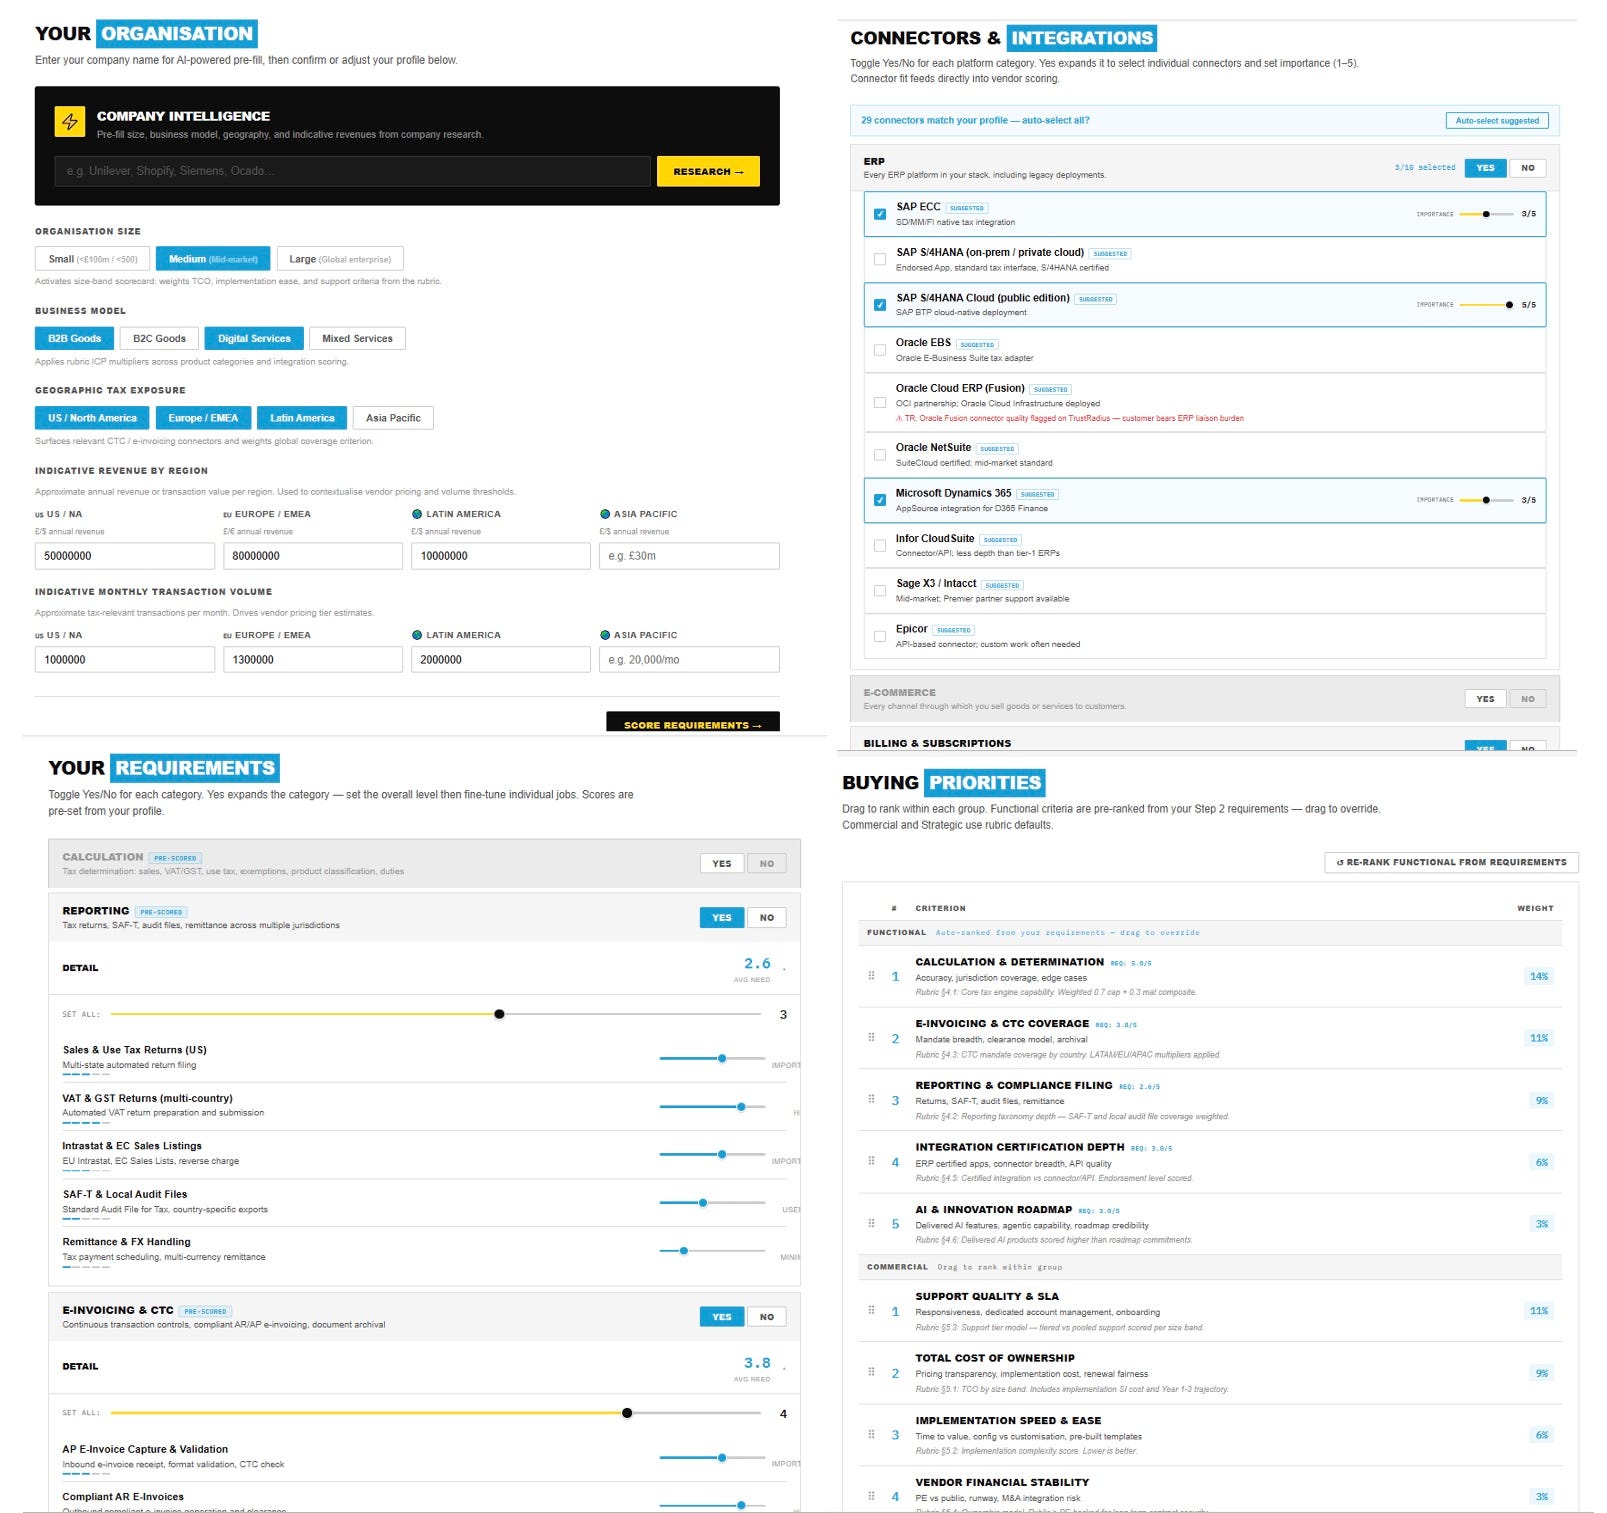
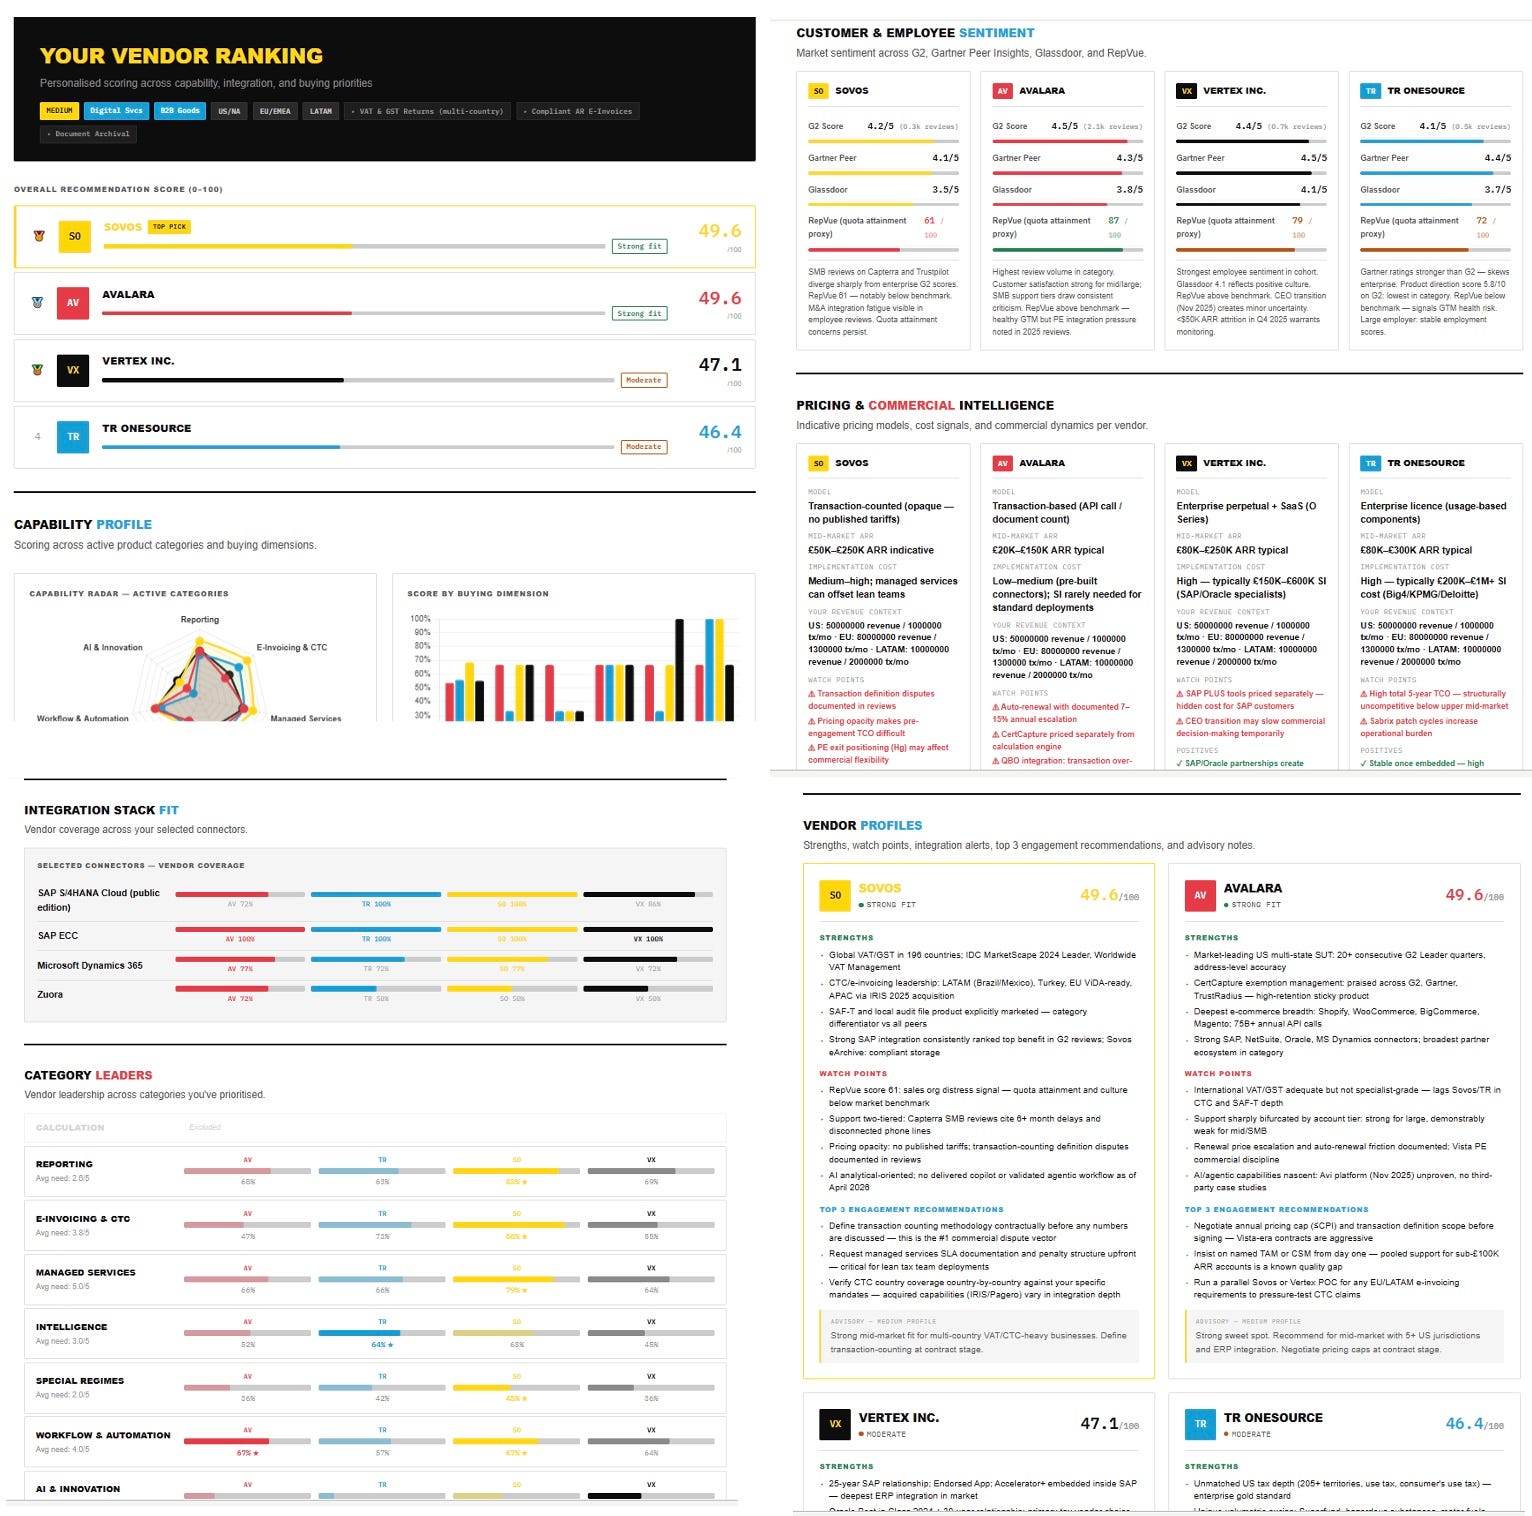
Below are a couple screenshots (don’t judge) of a tool I built that will customise a vendor comparison to a specific company, I’d love some feedback on it so if you’d like a free customised report, and the ability to tell your boss you used AI to do it (and keep your job a little longer) then message me.
Now for the rest of the platform comparison… ✌
🧨Vendor Showdown (Part 2)
The question “which vendor should we pick?” breaks cleanly into two separate problems, and vendors want you to conflate them: what’s your compliance problem, and who can solve it? vs. what’s your business model, and who serves your segment?
The first question is product. The second is fit.
BUSINESS MODEL FIT: WHERE REVENUE ACTUALLY LIVES
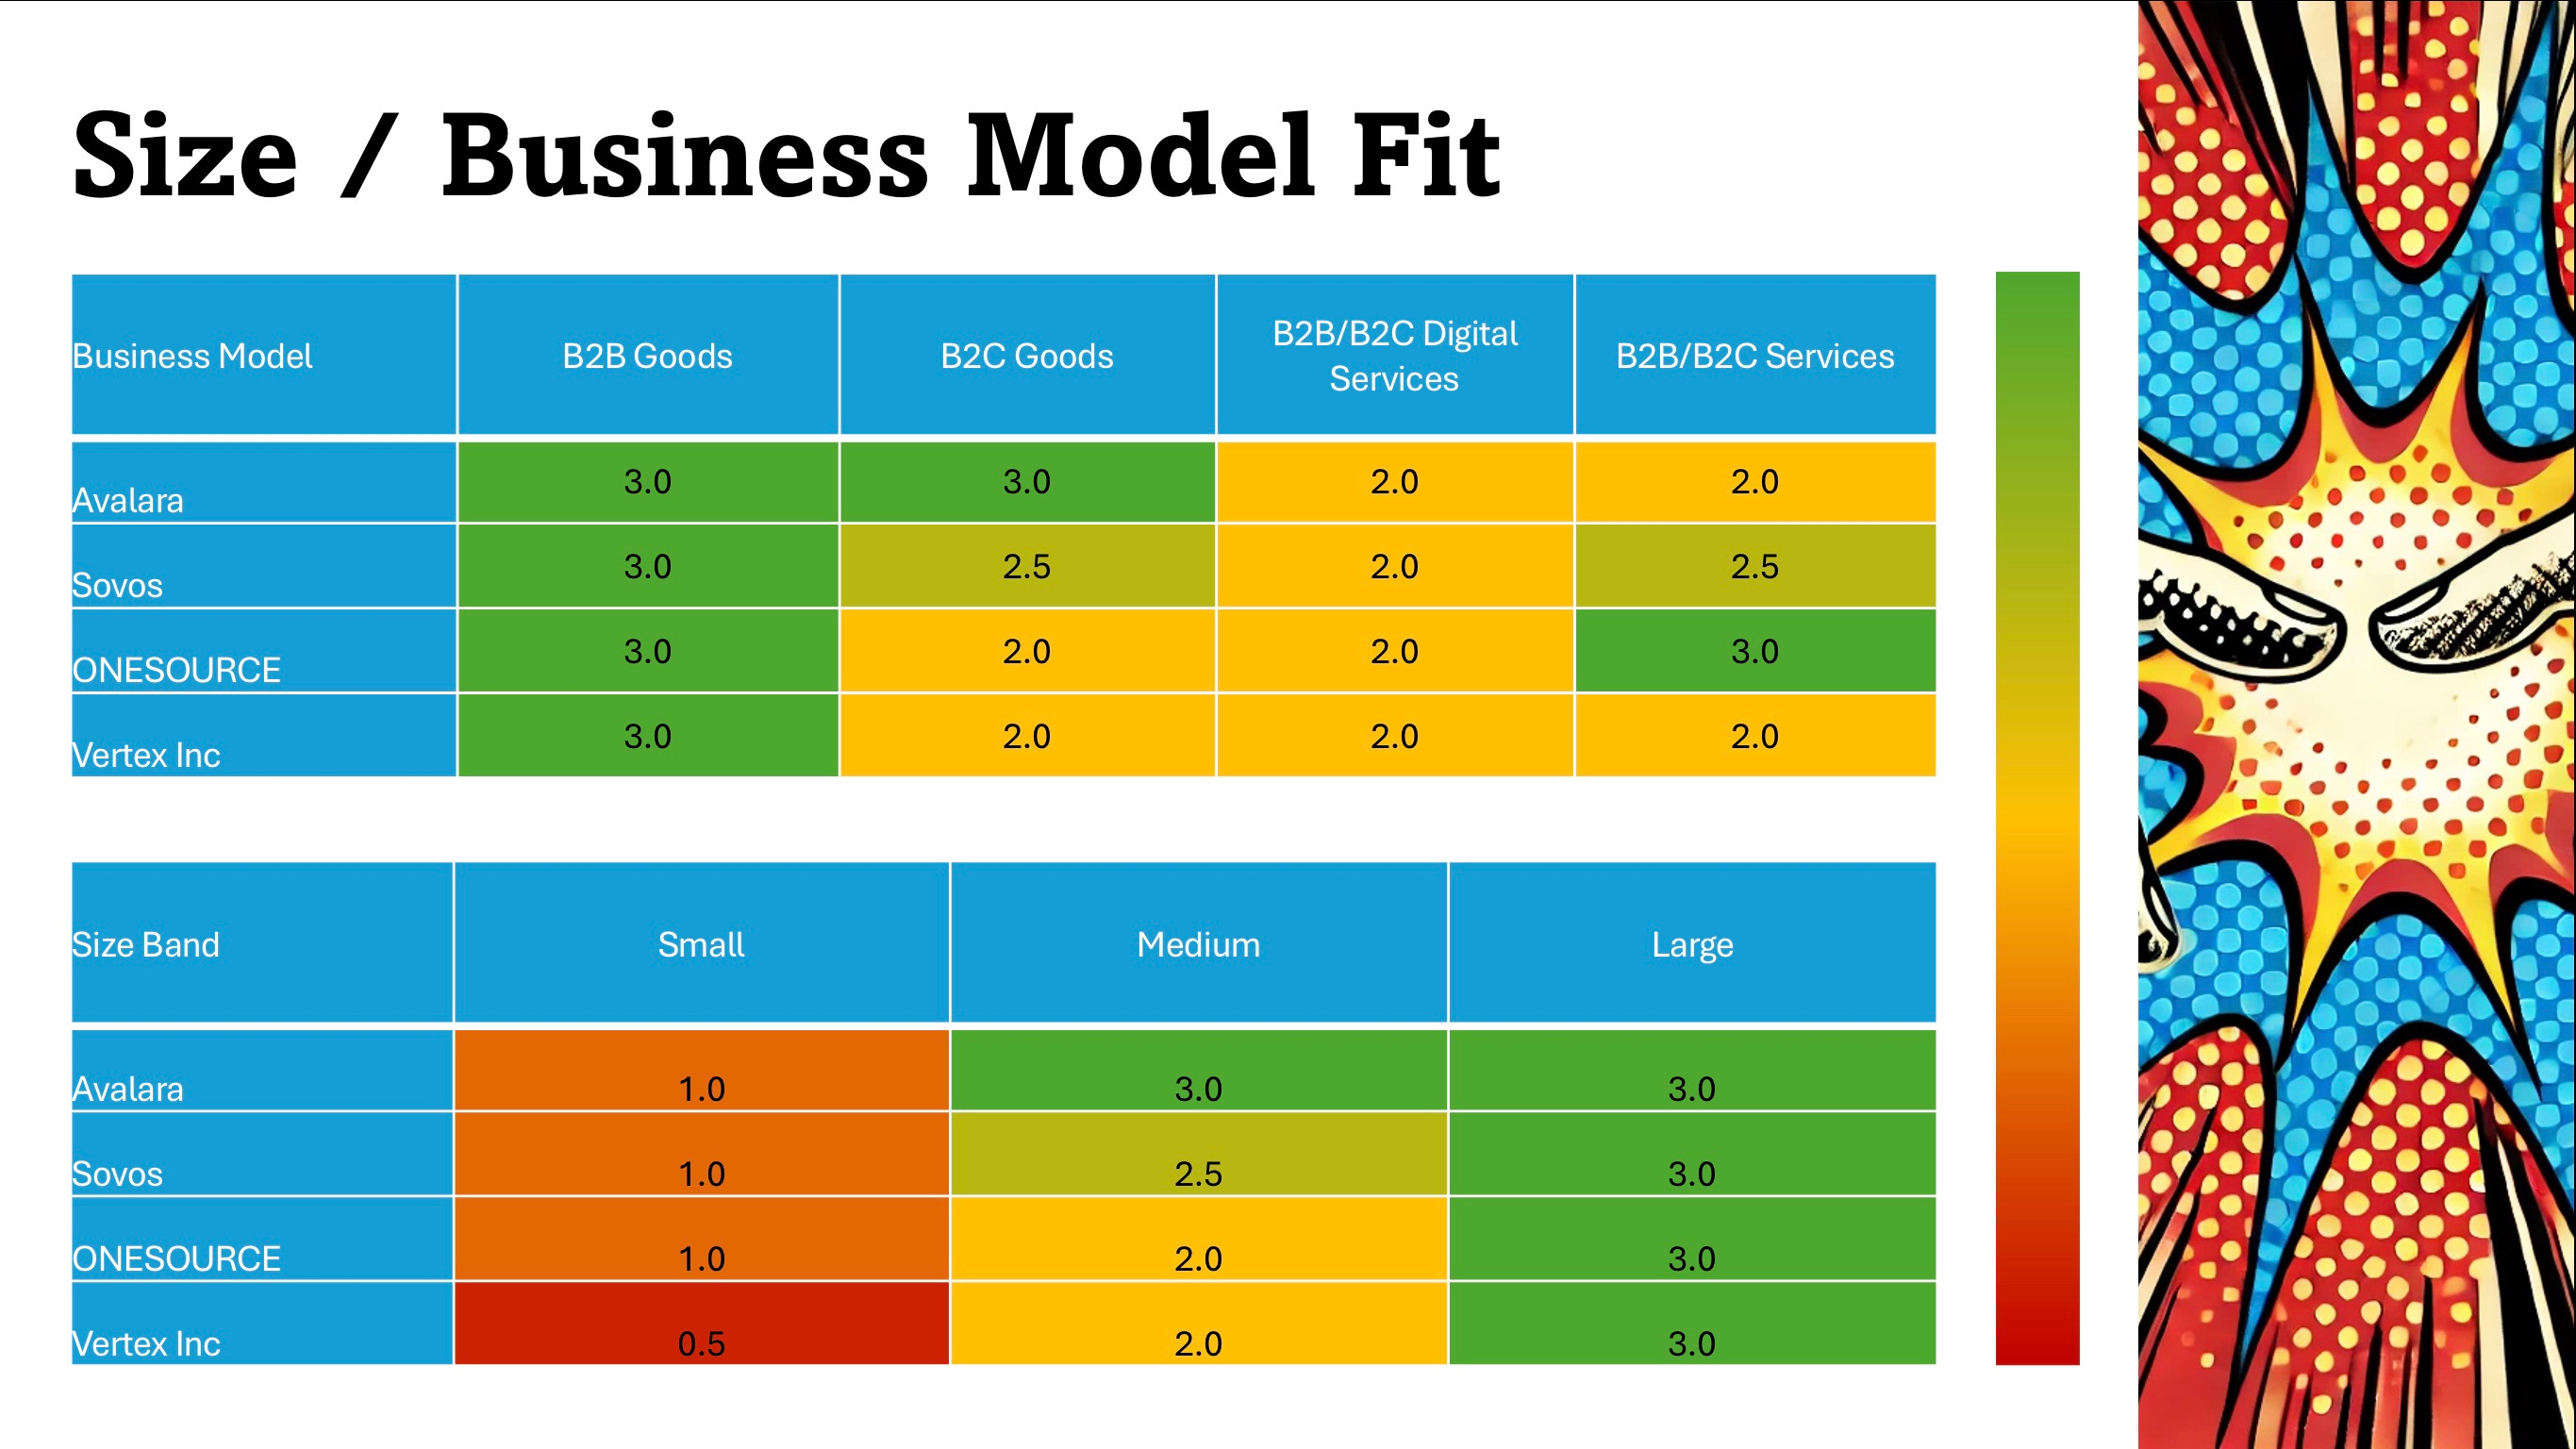
Avalara, Sovos, Thomson Reuters ONESOURCE, and Vertex all compete in B2B goods—manufacturers, wholesalers, multi-step supply chains—which is the centre of gravity for this vendor set. All four score between 2.5 and 3 (strong fit) here because the compliance problem is well-structured: sales/use tax in the US, VAT globally, CTC in emerging markets. Sovos and Thomson Reuters slight-lead on CTC depth; Avalara leads on integration breadth; Vertex leads on ERP maturity.
B2C goods—omnichannel retail, e-commerce, direct-to-consumer—shows sharper differentiation. Avalara’s 1,200 connectors and native Shopify/WooCommerce integrations make it the natural fit at scale for multi-jurisdiction e-commerce. Vertex’s Taxamo Assure offers the most structured EU e-commerce VAT managed service. Sovos is compelling only if you have material CTC obligations in LATAM or Italy. Thomson Reuters is viable only at large enterprise scale with POS deployment or omnichannel infrastructure.
B2B/B2C digital services—SaaS, marketplaces, platforms—is where all four uniformly underperform. None was architected around API-first, low-latency calculation and native subscription-billing platform integrations (Stripe, Zuora, Chargebee). Avalara least-bad here on billing integrations; Sovos and Vertex adequate; Thomson Reuters misaligned. If you’re digital-first, evaluate API-native specialists (Fonoa, Numeral, Anrok) first.
B2B/B2C services—professional services, consulting, financial services—is where Thomson Reuters’s Deloitte partnership reshapes competition. January 2026 managed services alliance where Deloitte operates global e-invoicing and e-reporting on ONESOURCE infrastructure is the single most structurally significant managed services development in this peer group. For large multinational professional services firms with lean tax functions, it’s a genuine differentiator. Sovos’s SAF-T capability is a close second.
Don’t shortlist based on vendor size or brand recognition. Shortlist based on whether the vendor’s actual product depth aligns with your revenue model.
SIZE BAND REALITIES: SMALL, MEDIUM, AND LARGE ARE DIFFERENT MARKETS
Small (< 50 employees): All four vendors are structurally over-engineered. Avalara is the least-bad option of this peer group for small e-commerce businesses, but post-Vista pricing escalation and support deterioration make even that mediocre. Sovos, Vertex, and Thomson Reuters are effectively not competitive at small scale. The market default is API-native disruptors (Kintsugi, TaxJar, Quaderno).
Medium (50–2,000 employees): This is the battleground. Avalara and Sovos are both credible, with Avalara slightly ahead on US complexity and Sovos ahead on international complexity. Vertex is viable if you’re SAP-centric and have serious multi-jurisdiction needs. Thomson Reuters enters only at the upper band ($200M+ revenue) with Big 4 support. Implementation cycles are 3–6 months; support quality bifurcates along large-account / everybody-else lines at Avalara and Sovos}; pricing transparency is a diligence requirement.
Large (2,000+ employees): All four are credible, and differentiation is product depth, ERP integration, and ownership dynamics. Vertex leads on sales org health (RepVue 62% quota attainment). Thomson Reuters leads on determination accuracy and Superfund depth. Sovos leads on CTC breadth. Avalara leads on integration ecosystem. You can shortlist any of the four at this tier—the real question is which specific strengths align with your obligations and which risks you’re comfortable living with.
CUSTOMER SENTIMENT: WHAT REVIEWS REALLY SAY
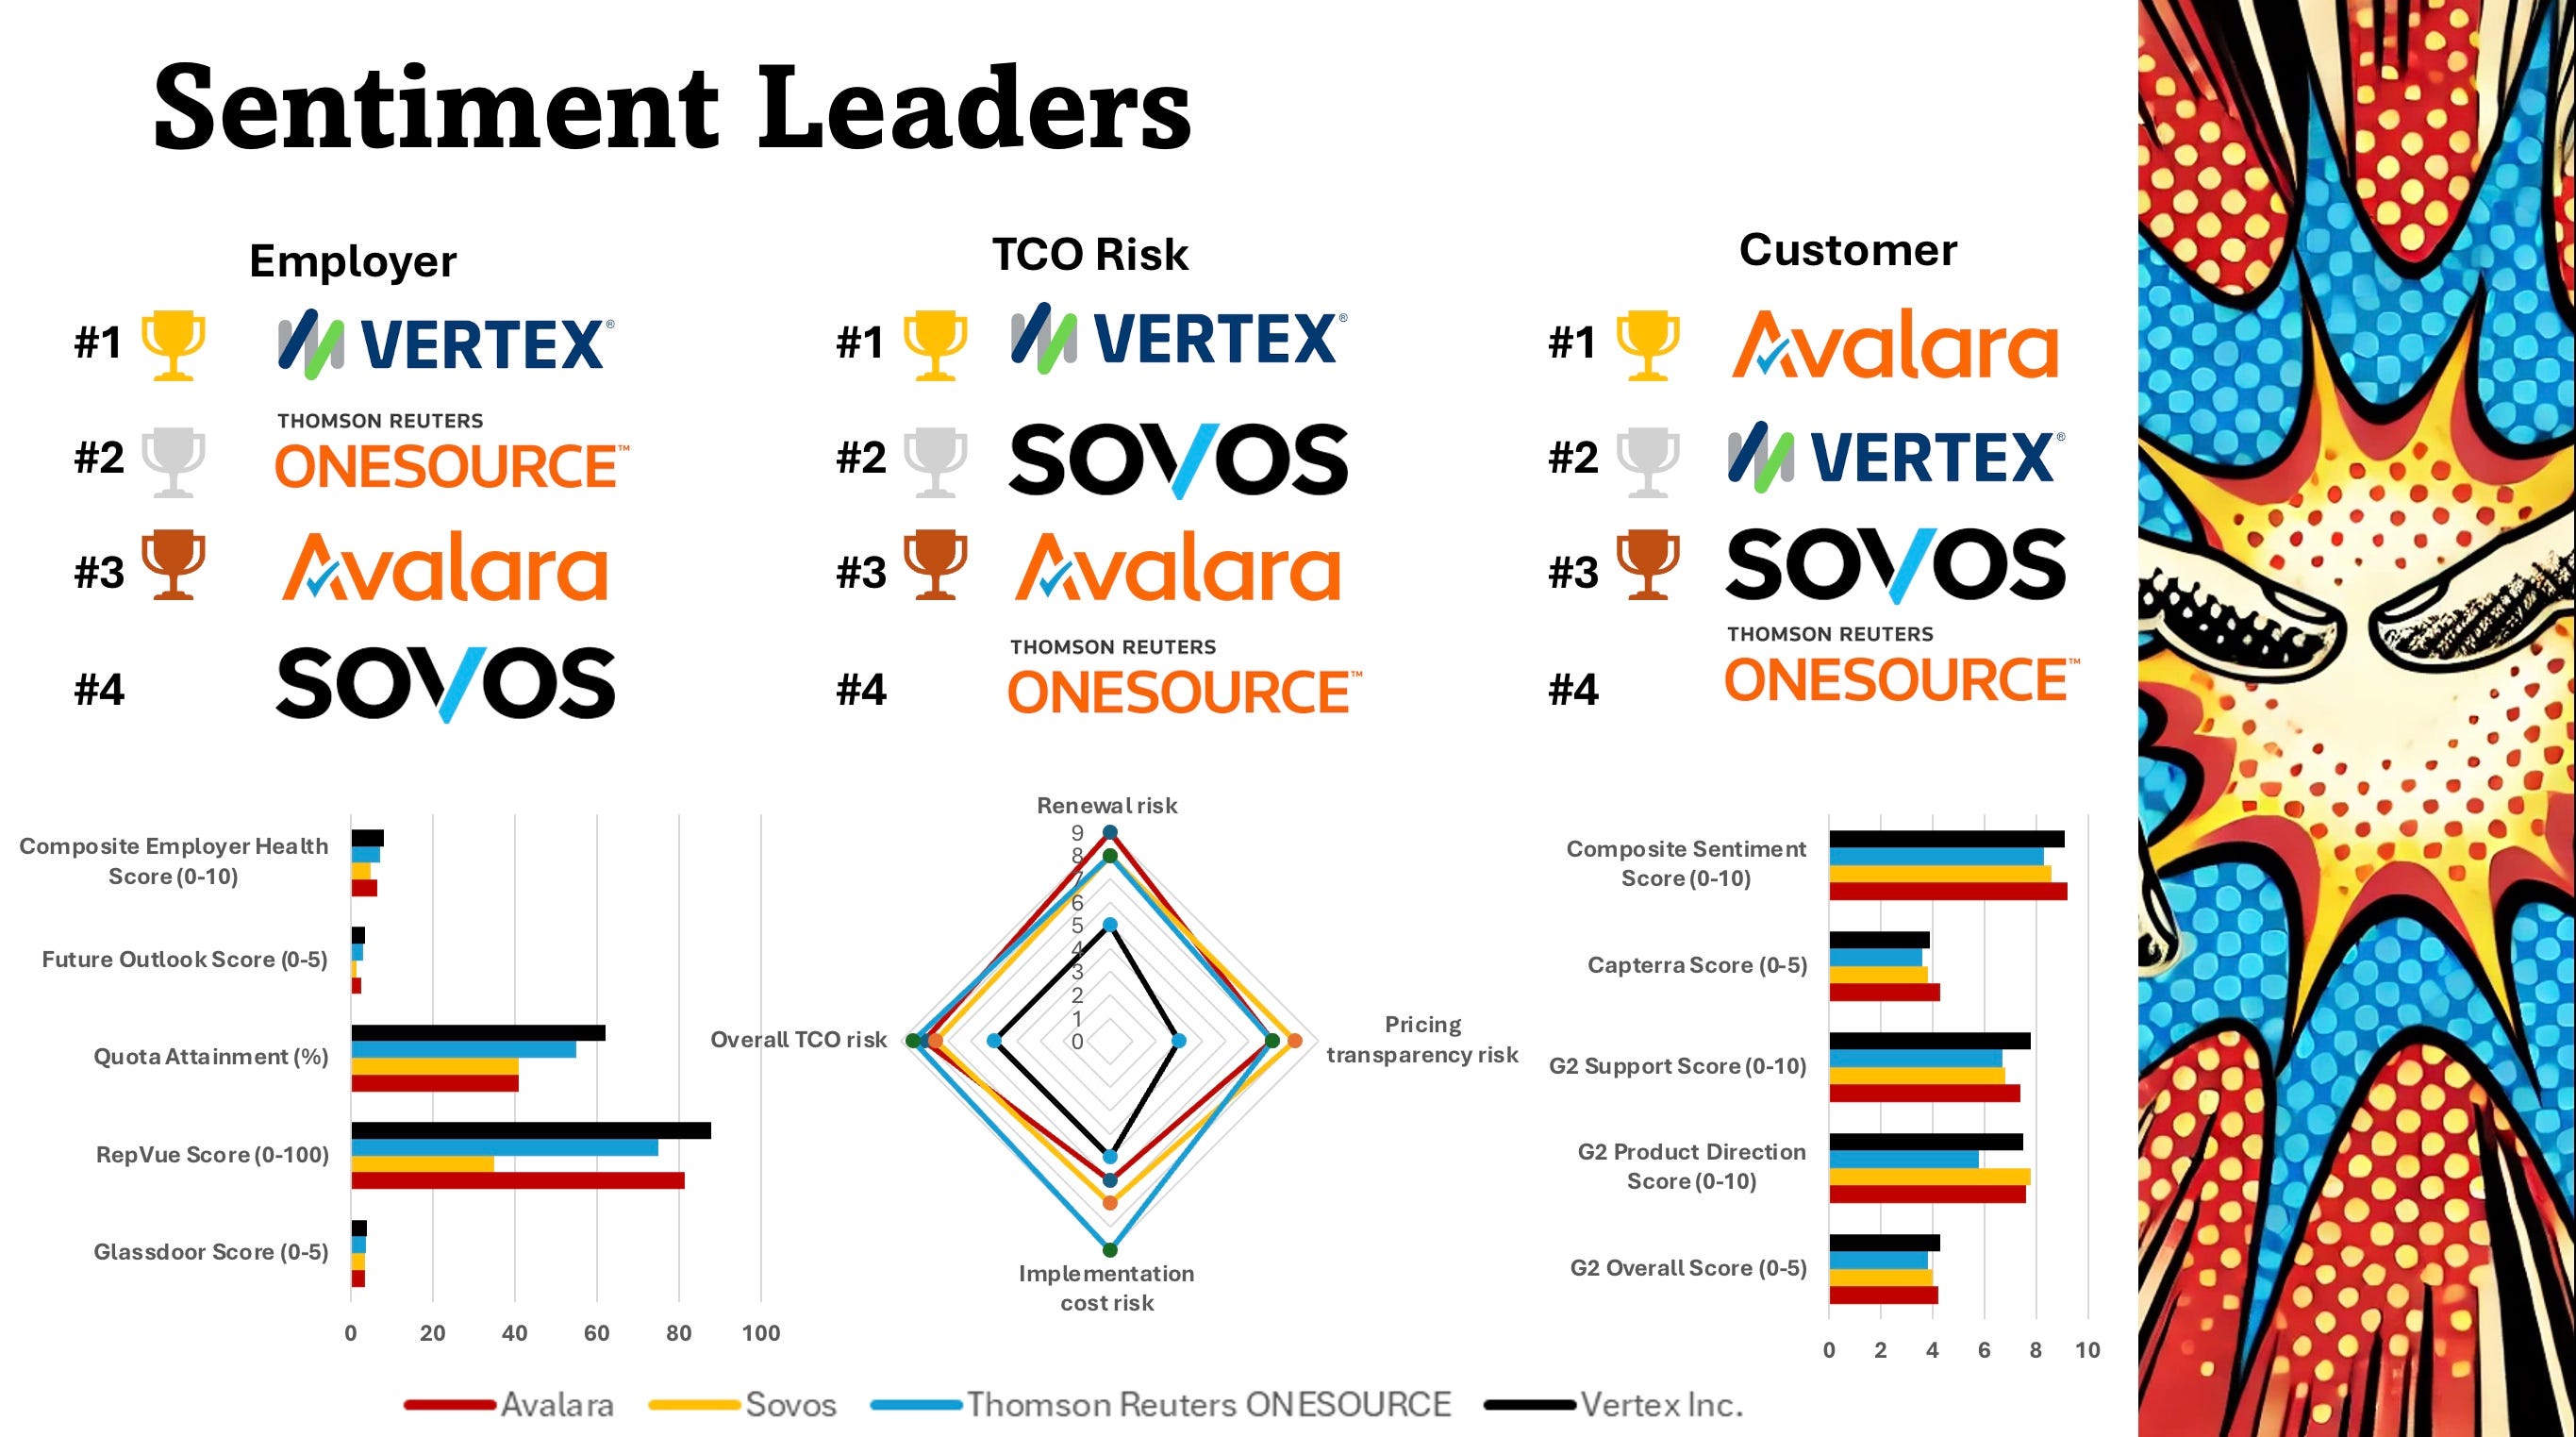
Avalara: G2 4.2, strongest overall product score in peer group. Customers praise US SUT determination, CertCapture exemption capability, and 1,200 connector breadth. Strong implementation narratives for large accounts. On Capterra and TrustRadius, sentiment drops significantly due to post-Vista support concerns, renewal pricing escalation (30–50% increases documented), and transaction-definition disputes. Mid-market and SMB reviews flag slow response times and support quality deterioration post-acquisition.
Sovos: G2 4.0, strong themes around VAT breadth (196 countries), SAF-T capability, and CTC regional depth. Large, strategic customers report solid implementation and ongoing account management. Capterra and TrustRadius significantly lower, reflecting SMB and legacy customer pain: six-month support tickets, billing disputes, transaction-counting disagreements where annual bills frequently exceed quotes. The bifurcated experience is stark—enterprise customers satisfied, mid-market customers frustrated.
Thomson Reuters ONESOURCE: G2 3.8, strong on calculation accuracy, SAP integration maturity, and Pagero e-invoicing breadth. Determination accuracy and Big 4 channel endorsement matter to enterprise buyers. Product direction score notably weak (5.8/10), a signal that competitive concern is real. No material presence on Capterra or TrustRadius, suggesting minimal SMB adoption. Customer sentiment concentrated in enterprise segment; limited mid-market narrative.
Vertex Inc.: G2 4.3, highest overall score. Strong on ERP integration depth (SAP, Oracle), US SUT accuracy, and account team quality. Customers consistently praise implementation support and continuity. Reporting and analytics capability gaps most consistently cited negative in reviews—this is the one area where Vertex clearly lags peers. Mid-market customers report better support experience than Avalara or Sovos at comparable scale.
The headline pattern: G2 and Gartner Peer Insights sit 3.8–4.3 across all four with strong enterprise satisfaction. Capterra and TrustRadius show sharper bifurcation—Avalara and Sovos experience most mid-market friction; Vertex maintains support continuity; Thomson Reuters has minimal SMB presence. The real picture for mid-market buyers is Avalara (30–50% renewal shock, slow support) or Sovos (transaction disputes, slow tickets) or Vertex (solid support, reporting gaps).
EMPLOYEE SENTIMENT AND WHAT IT PREDICTS
Vertex Inc. Glassdoor 3.9, RepVue 62% quota attainment, mid-to-strong future outlook. Sales org is healthy. Your account team will probably still be there at year 2 renewal. This is the only vendor in this set with institutional continuity across implementation cycles.
Thomson Reuters Glassdoor 3.7, public company governance, institutional stability. Slow to move, but reliable. Your account team is likely embedded in a managed services alliance if you’ve opted into that model. Talent turnover predictable and manageable.
Avalara Glassdoor 3.35, RepVue signals post-Vista pressure. Quota attainment 41%, future outlook weak. Sales org churn is real and documented. Your AE may not be there at renewal. Mid-market accounts report continuity gaps and relationship discontinuity across quarters.
Sovos Glassdoor 3.4, RepVue 41% quota attainment, future outlook 1.4/5.0—actively concerning. Sales org under strain. HgTA exit positioning and leadership churn create active turnover risk. Your account team’s continuity is not guaranteed. This is the most concerning signal in the entire peer set on org health.
For mid-market buyers, account team stability is predictive of go-live quality, implementation continuity, and renewal friction. This data matters as much as product features.
PRICING: THE COMMON RISK ACROSS ALL FOUR
All four vendors are sales-led with opaque initial pricing. The critical buyer protection is contractual clarity at signature: explicit transaction definition with a cap on definitional expansion, annual uplift ceiling (ideally CPI-linked), clear implementation cost, and no forced bundling.
Avalara: Transaction volume + modules. Most documented renewal escalation in peer group (30–50% increases reported). TAM support tier priced separately. Highest buyer friction and greatest pricing variability.
Sovos: Transaction volume + jurisdiction count + modules. Transaction-counting disputes are the primary pain point—annual bills frequently exceed quotes. Renewal pricing escalation documented and contested.
Thomson Reuters: High implementation cost (often equals or exceeds licence). CIP Certified Implementer Programme tier structure creates ongoing professional services dependency. Annual uplift negotiable but support tiers add cost.
Vertex: Most transparent. ARR model + public financials. Annual uplift 7–12% documented but negotiable down to CPI+2–3% with multi-year commitment. Lowest pricing surprise risk.
THE BOTTOM LINE: CHOOSE BASED ON ACTUAL CONSTRAINTS
If you’re Large B2B goods on SAP: Vertex or Sovos belong on your shortlist. Vertex for sales org stability and ERP depth; Sovos for CTC breadth. Lock in renewal caps before signing.
If you’re Mid-market with US focus: Avalara is still default. Structure your contract to cap pricing escalation. Be prepared to renegotiate hard at renewal.
If you’re Mid-market with international complexity: Sovos or Thomson Reuters}. Budget 3–6 months for implementation. Treat it as a platform programme.
If you’re B2C e-commerce: Avalara}. Adequate for scale. Just manage the renewal pricing risk.
If you’re digital-native and API-first: Look beyond this set first. This peer group is too-heavy for your culture and velocity.
If you’re Small: This peer group is over-engineered for you. Look to API-native alternatives.
The vendors in this set aren’t interchangeable. Pick based on which vendor’s actual strengths align with your actual constraints—not on brand size or glossiest marketing. That’s the only way to avoid systematic overpay and implementation disappointment.
Want a copy of the full 60+ page report?

A selection of of opportunities to connect in person and interact online over the next few weeks
May 2026
Tax Accounting in Action: Pillar 2 Unlocked (In-Person)
Deloitte Belgium | May 18–19, 2026 | Belgium
A comprehensive two-day workshop focused on Pillar 2 tax accounting changes, their practical implications, and implementation strategies.
Event Page →
Join EY, Meridian, Jaguar Land Rover, and SAP: Exclusive Tax and Trade Leadership Event (In-Person)
EY / Meridian Global Services | May 19, 2026 | EY Offices, London Bridge, London, UK
Brings together industry peers to explore the evolving landscape of tax and trade, focusing on the latest trends and best practices in global compliance. Contact Ruby Buckland at EY to register.
Event Page →
Trade and Tariff Tuesdays — May (Webinar)
Avalara | May 19, 2026 | Online/Virtual
Avalara experts break down key global trade issues and their business implications in this recurring webinar series.
Register →
Tax Intelligence 2026 / Evintel (In-Person)
Fintua / VAT IT | May 20–21, 2026 | Scandic Frankfurt Museumsufer, Frankfurt, Germany
Specialist summit for senior tax and technology professionals exploring the challenges and opportunities of governing VAT data and e-invoicing at scale.
Event Page →
Gartner Finance Symposium/Xpo™ 2026 (In-Person)
Vertex Inc | May 27–29, 2026 | Gaylord National Resort, National Harbor, MD, USA
Finance leaders forum with Vertex providing practical strategies on indirect tax compliance within the enterprise technology ecosystem.
Register →
What to Expect from Global Tax Policy and Controversy in 2026 (Webinar)
EY | May 28, 2026 | Online/Virtual
A panel of EY Tax Policy and Controversy leaders discusses strategic priorities for tax departments as they address changing global tax policy and enforcement landscapes.
Register →
June 2026
Tax Tech Live 2026 (In-Person)
Tax Systems | June 2, 2026 | London, UK
Exclusive customer-focused event bringing together tax professionals for a day of cutting-edge insights, expert discussions, and the latest innovations in tax technology. Contact your Tax Systems Client Executive to register.
Event Page →
Private Equity & Private Capital Quarterly Tax Update — Q2 2026 (Webinar)
EY | June 4, 2026 | Online/Virtual
Quarterly update on strategic influences shaping private equity and capital funds, including US legislative updates, global macro trends, and tax implications.
Register →
8th Annual VAT Management Summit (In-Person)
Fintua (Gold Sponsor) | June 9–10, 2026 | The Tower Hotel, London, UK
Summit bringing together industry leaders to explore the latest developments in VAT compliance, digital reporting, and regulatory change.
Event Page →
*any organisers or events I’ve missed? please let me know.

A curated selection of blogs, white-papers and on demand content published by multiple organisartions across the landscape, organised into a themed learning path.
MONTH TWO · MAY 2026
E-Invoicing, CTCs & Real-Time Compliance
Belgium is now live, Brazil is overhauling its entire indirect tax system, Poland’s KSeF mandate is entering enforcement, and France’s September 2026 deadline is approaching. The e-invoicing landscape has never moved faster.
Week 7 · 19–23 May
Platform Strategy: ERP Integration, Consolidation & Architecture
19 📖 Leading the Charge: E-Invoicing as the Cornerstone of Future Compliance Vertex Inc. 10–12 min
20 📖 E-Invoicing Transformation: How to Get It Right Pagero (TR)10–12 min
21 🎥 E-Invoicing in Eastern Europe: KSeF, ViDA, Romania, Hungary & Beyond Pagero (TR) 45 min
Week total: 2 articles + 1 webinar · ~65–69 min
Week 8 · 26–30 May
Intelligence & Emerging Markets: SYNAPSE Insights, Brazil’s Reform & AI in Indirect Tax
22 📖 5 Key Indirect Tax Trends from SYNAPSE 2026 Fonoa 10–12 min
23 📖 Brazil 2026 Tax Reform: Key E-Invoicing Changes for Businesses Fonoa 10–12 min
24 🎥 Embracing the Future of Tax Compliance with AI Avalara 45–60 min
Week total: 2 articles + 1 webinar · ~65–84 min
MONTH THREE · JUNE–JULY 2026
Direct Tax, Pillar Two & Corporate Tax Provision
The GIR filing window is now open — calendar-year groups face a June 30, 2026 deadline for their first live GloBE Information Return. The OECD Side-by-Side Package has materially changed what US-headquartered MNEs must do, but QDMTTs remain, GIR obligations continue, and non-US MNEs face unchanged IIR/UTPR exposure. This month goes deep on the technology implications of all of it.
Week 9 · 2–6 June
Pillar Two 2026: The Side-by-Side Package and What It Means for Technology
25 📖 QDMTT: Stay Ahead of the Global Minimum Tax Curve Orbitax (TR) 12–15 min
26 📖 OECD Side-by-Side Package: Relief for US Multinationals RSM US 12–15 min
27 🎥 Pillar Two Compliance: Grant Thornton & Orbitax Strategies Orbitax / Grant Thornton 60 min · CPE
Week total: 2 articles + 1 webinar · ~84–90 min
Week 10 · 9–13 June
Unpacking the Side-by-Side Package & the First GIR Filing Cycle
Having established the context in Week 9, this week goes deeper into the technical and compliance architecture of the new Pillar Two framework — including an authoritative technical breakdown of the four new safe harbours (SbS, UPE, SBTI, and Simplified ETR) and what GIR data collection must look like in practice for first-wave filers.
28 📖 The New Pillar Two Framework: Unboxing the Side-by-Side Package Alvarez & Marsal 15–18 min
29 📖 2026 Indirect Tax Trends Vertex Inc. 8–10 min
30 🎥 Seamless Tax Data Integration: From Any System to Pillar Two Compliance Orbitax / Deloitte 45–60 min
Week total: 2 articles + 1 webinar · ~68–88 min
Month Two/Three total: 8 articles + 4 webinars · ~282–331 min
*any cool content I’ve missed? please let me know.

A selection of open roles across tax tech vendors and tax advisory/consulting businesses who are involved in tax technology.
Use the column headers to sort, or the (new) search function and don’t forget to navigate all pages!
*I do this using an AI agent and due to the volume, I don’t check every link, so please let me know if any of these don’t work or have disappeared when you follow them.
✌ Last thoughts
Thanks again for reading! If you have any feedback, suggestions, want to contribute, share gossip or would like to work together in any way, email me here or hit the button below!