

🤷♂️ TL;DR update on Vertex announcement, 364 Jobs, 15 events, 5:28 hours of learning and 1 vendor showdown (Indirect Tax Platforms)
❤ Helping out at The Nexus
What a week! After Vertex’s announcement last week, my inbox was jammed up with requests for support, with many of you now subscribers and hopefully finding use in the job links that I’ve shared. Please let me know how you’re getting on in your searches and if I can help more…
This week I’ve added a king-size batch for anyone actively looking and I know there are some hiring manager and recruiter subscribers, so if you think you can help, then please get active on the chat here or jump in on my LinkedIn post
A huge amount of work has gone into this week’s issue. Behind each of the last 4 vendor spotlights, is a substantial “analyst report” style profile that I’ve created and now they’ve all been combined into a single 60 page comparitive study. I think the result is pretty awesome and I’m proud to share extracts from it with you below, there’s a tonne of data so it’ll span this and next week’s issues.
Now help me to help you!
Firstly, I would love for more people to see the full report(s), so if any of you would like to receive a free version of an individual vendor profile or the full version of this week’s “showdown” report, please message me at nexustaxnews@gmail.com, all I ask for in return is your feedback.
I’ve also been testing a tool I’ve developed to tailor the output to a specific company/use case, and I would love volunteers (particularly any in house tax teams or consultants that recently have, or are currently evaluating vendors). If you’re happy spend 15-20 minutes going through this onlie with me, I’ll happily share the output with you and keep you in mind for future freebies/shout outs etc.
Now let’s see how the big 4 platforms stack up… ✌
🧨Vendor Showdown
Four vendors. Similar starting points but four fundamentally different strategic bets on how enterprise indirect tax gets built, operated, and scaled in a market fractured by regulatory acceleration & AI uncertainty.
When you sit them side by side—Avalara, Sovos, Thomson Reuters ONESOURCE, and Vertex Inc.—the headline numbers look interchangeable. Combined, they represent roughly $2.4–2.7 billion in estimated annual indirect tax revenue, serve over 150,000 customers, and collectively process tens of billions of transactions every year. But the architectural DNA beneath those numbers tells an entirely different story. And that story matters far more to your platform selection than any marketing deck will suggest.
ARCHITECTURE, OWNERSHIP & PRODUCT STRATEGY
Avalara and Vertex were built from the ground up to own US sales and use tax determination with unmatched depth and breadth. Avalara‘s 1,200 pre-built connectors and transaction-volume dominance in e-commerce echo its origins as a developer-first SaaS play; Vertex‘s 12,000-jurisdiction US engine and 47-year heritage in tax calculation accuracy reflect its pedigree as an enterprise calculation backbone. Their expansion into VAT, CTC compliance, and emerging market mandates reads as a layering exercise: strong US foundation, then build or acquire internationally. The architecture still reflects that sequence.
Sovos and Thomson Reuters ONESOURCE and their acquired businesses were engineered with global VAT and CTC mandate infrastructure at their centre. Thomson Reuters brings the editorial engine and content distribution of a publicly listed media conglomerate; Sovos was built as an acquisition-driven platform, assembling specialists in US SUT, EU VAT reporting, LATAM and European CTC depth, and most recently APAC. Both treat US compliance as a module within a globally native architecture, not as the starting point.
A large multinational with simultaneous complexity in US state tax, EU ViDA/SAF-T, Brazil NF-e, and Italy real-time reporting will find Sovos and Thomson Reuters architecturally aligned to the problem domain. An Avalara or Vertex customer will run into uncovered use cases. All providers will leave you integrating products, bridging portals, and managing architecture sprawl to some degree.
On ownership: Vertex is the only publicly listed pure-play. Thomson Reuters is publicly listed at corporate scale, meaning institutional governance, talent stability, and honoured support SLAs. Avalara and Sovos are PE-backed, and the evidence is consistent: post-acquisition cost discipline has materially impacted support quality at the mid-market tier. Avalara‘s TAM support is priced separately; Sovos‘s quota attainment dropped to 41%, signalling real org churn. For mid-market buyers, that ownership dynamic is the difference between a vendor investing in support continuity and one optimising for EBITDA margin.
DEPTH VS. BREADTH: THE DEFINITIVE TRADE-OFFS
Every vendor in this group is simultaneously best-in-class at something and clearly second tier at something else. Understanding that trade-off is the core of shortlisting discipline.
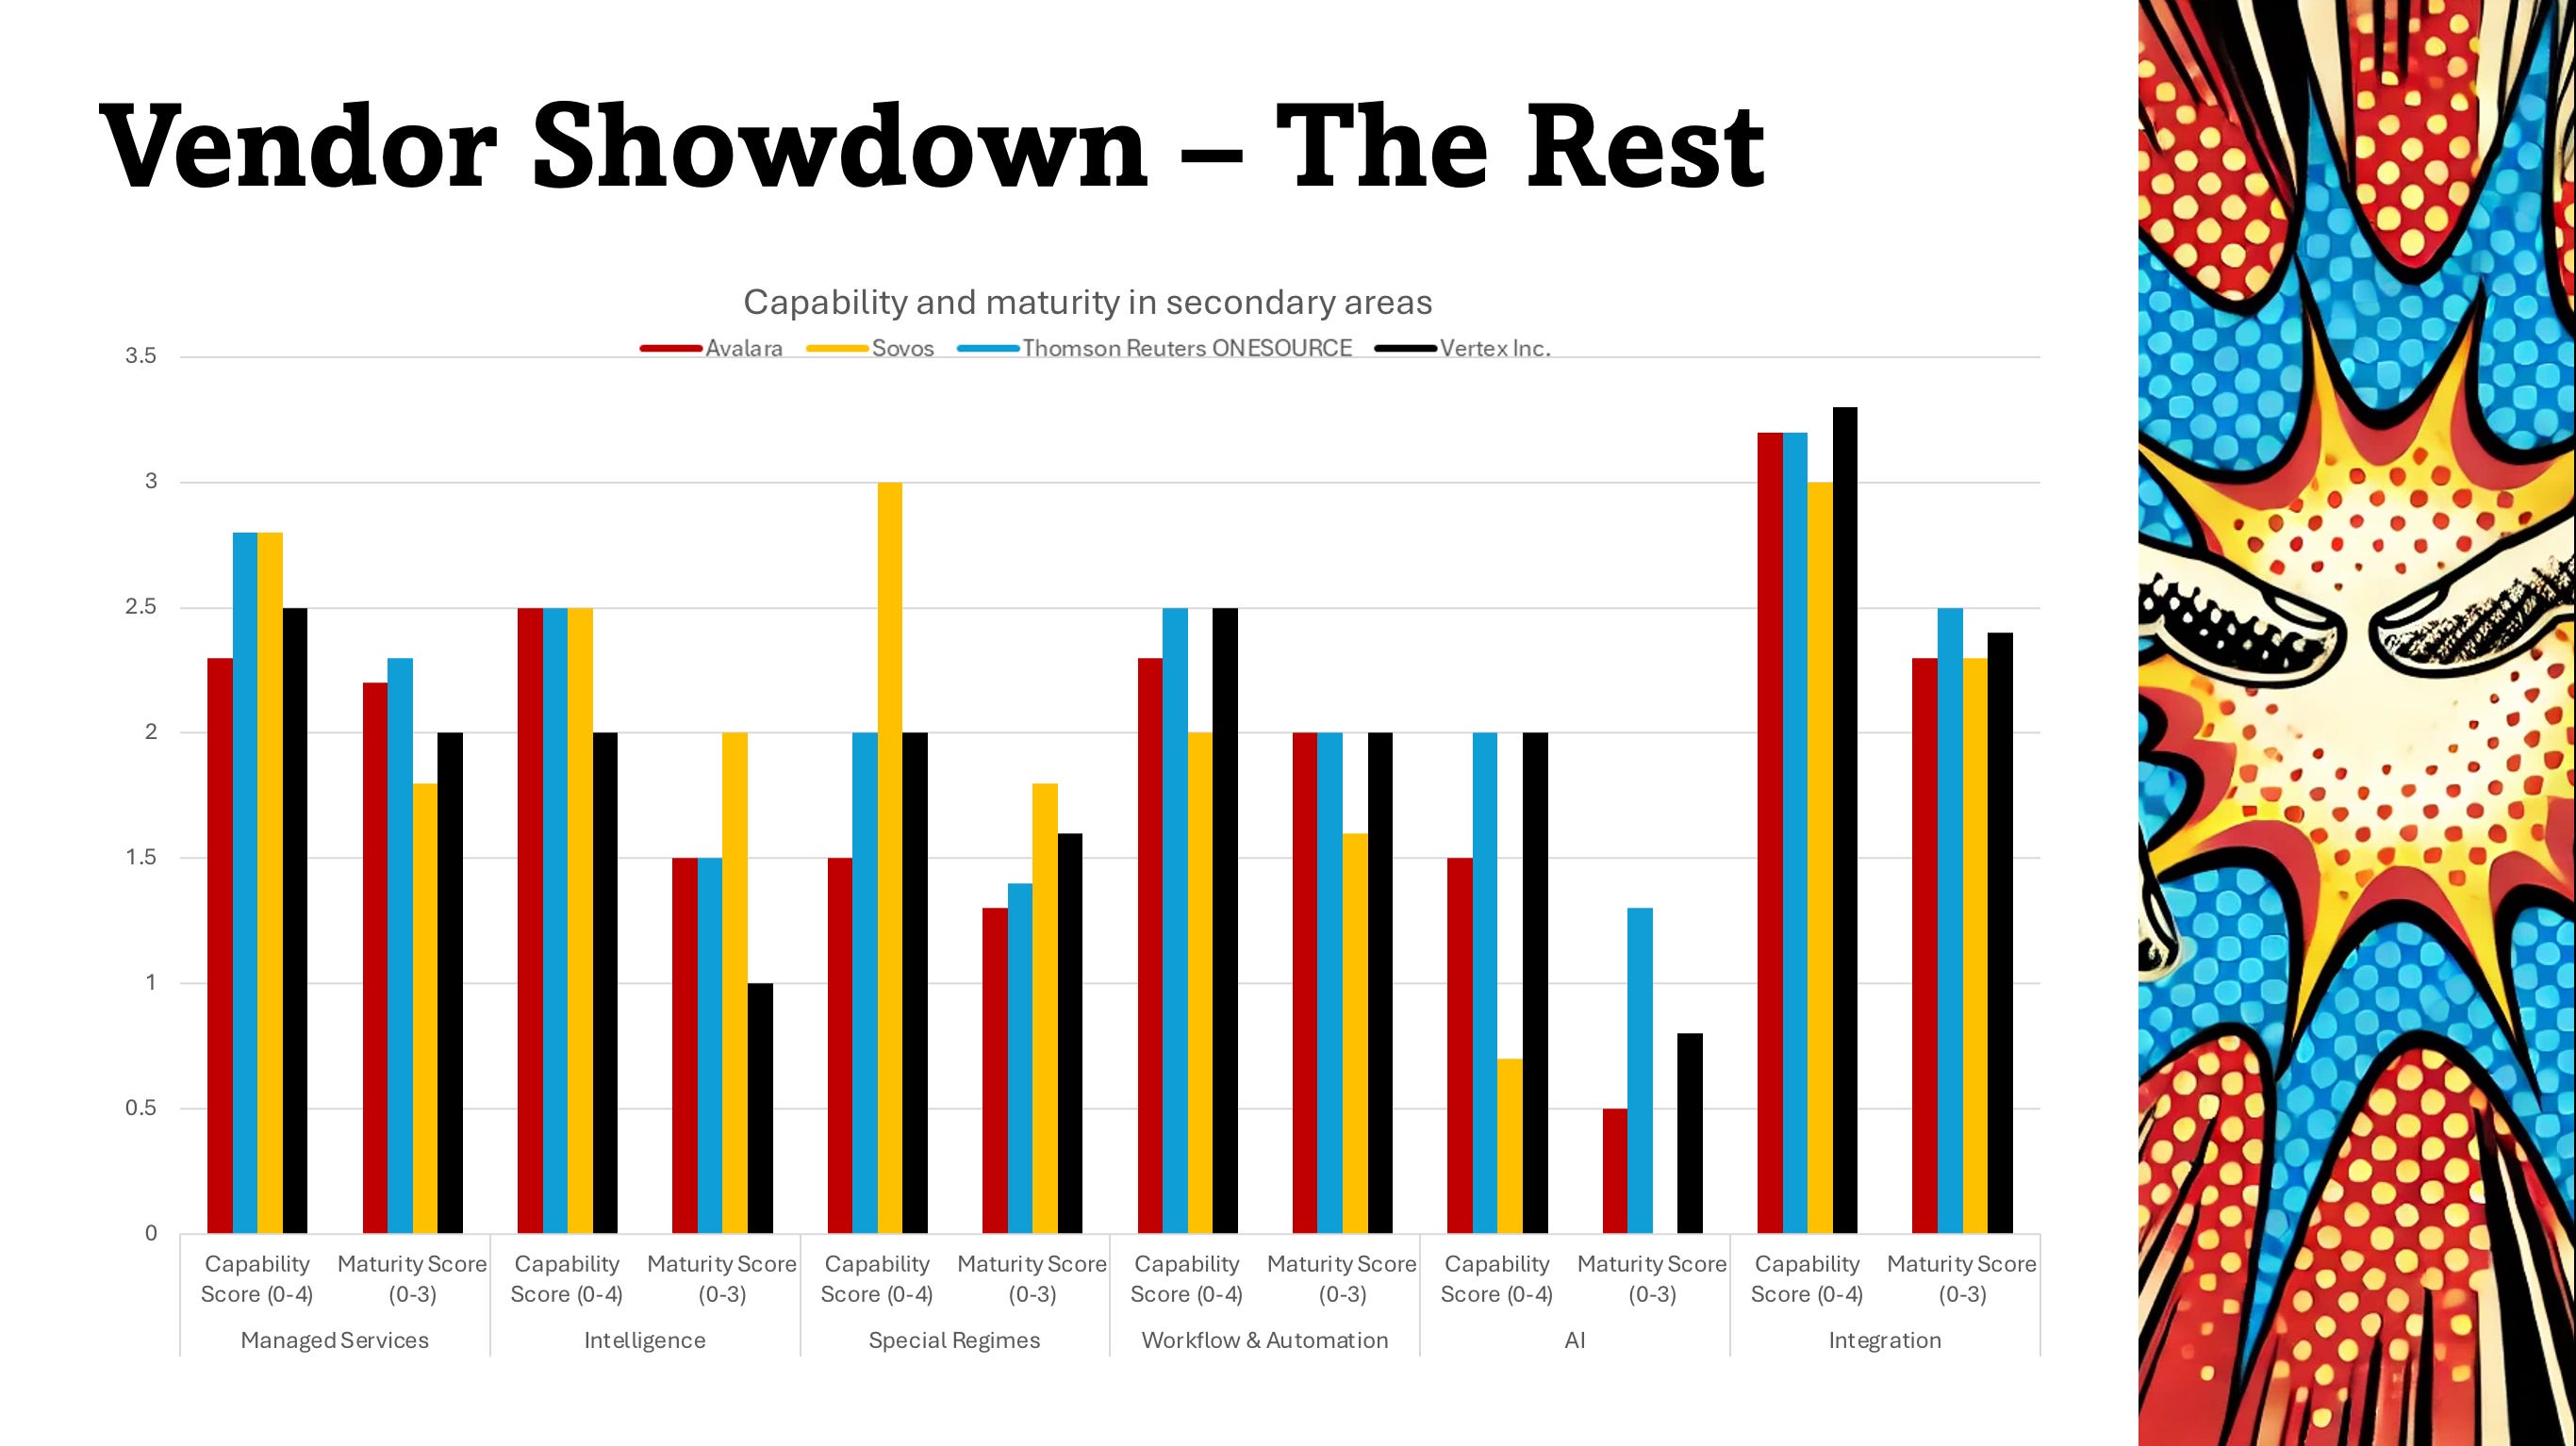
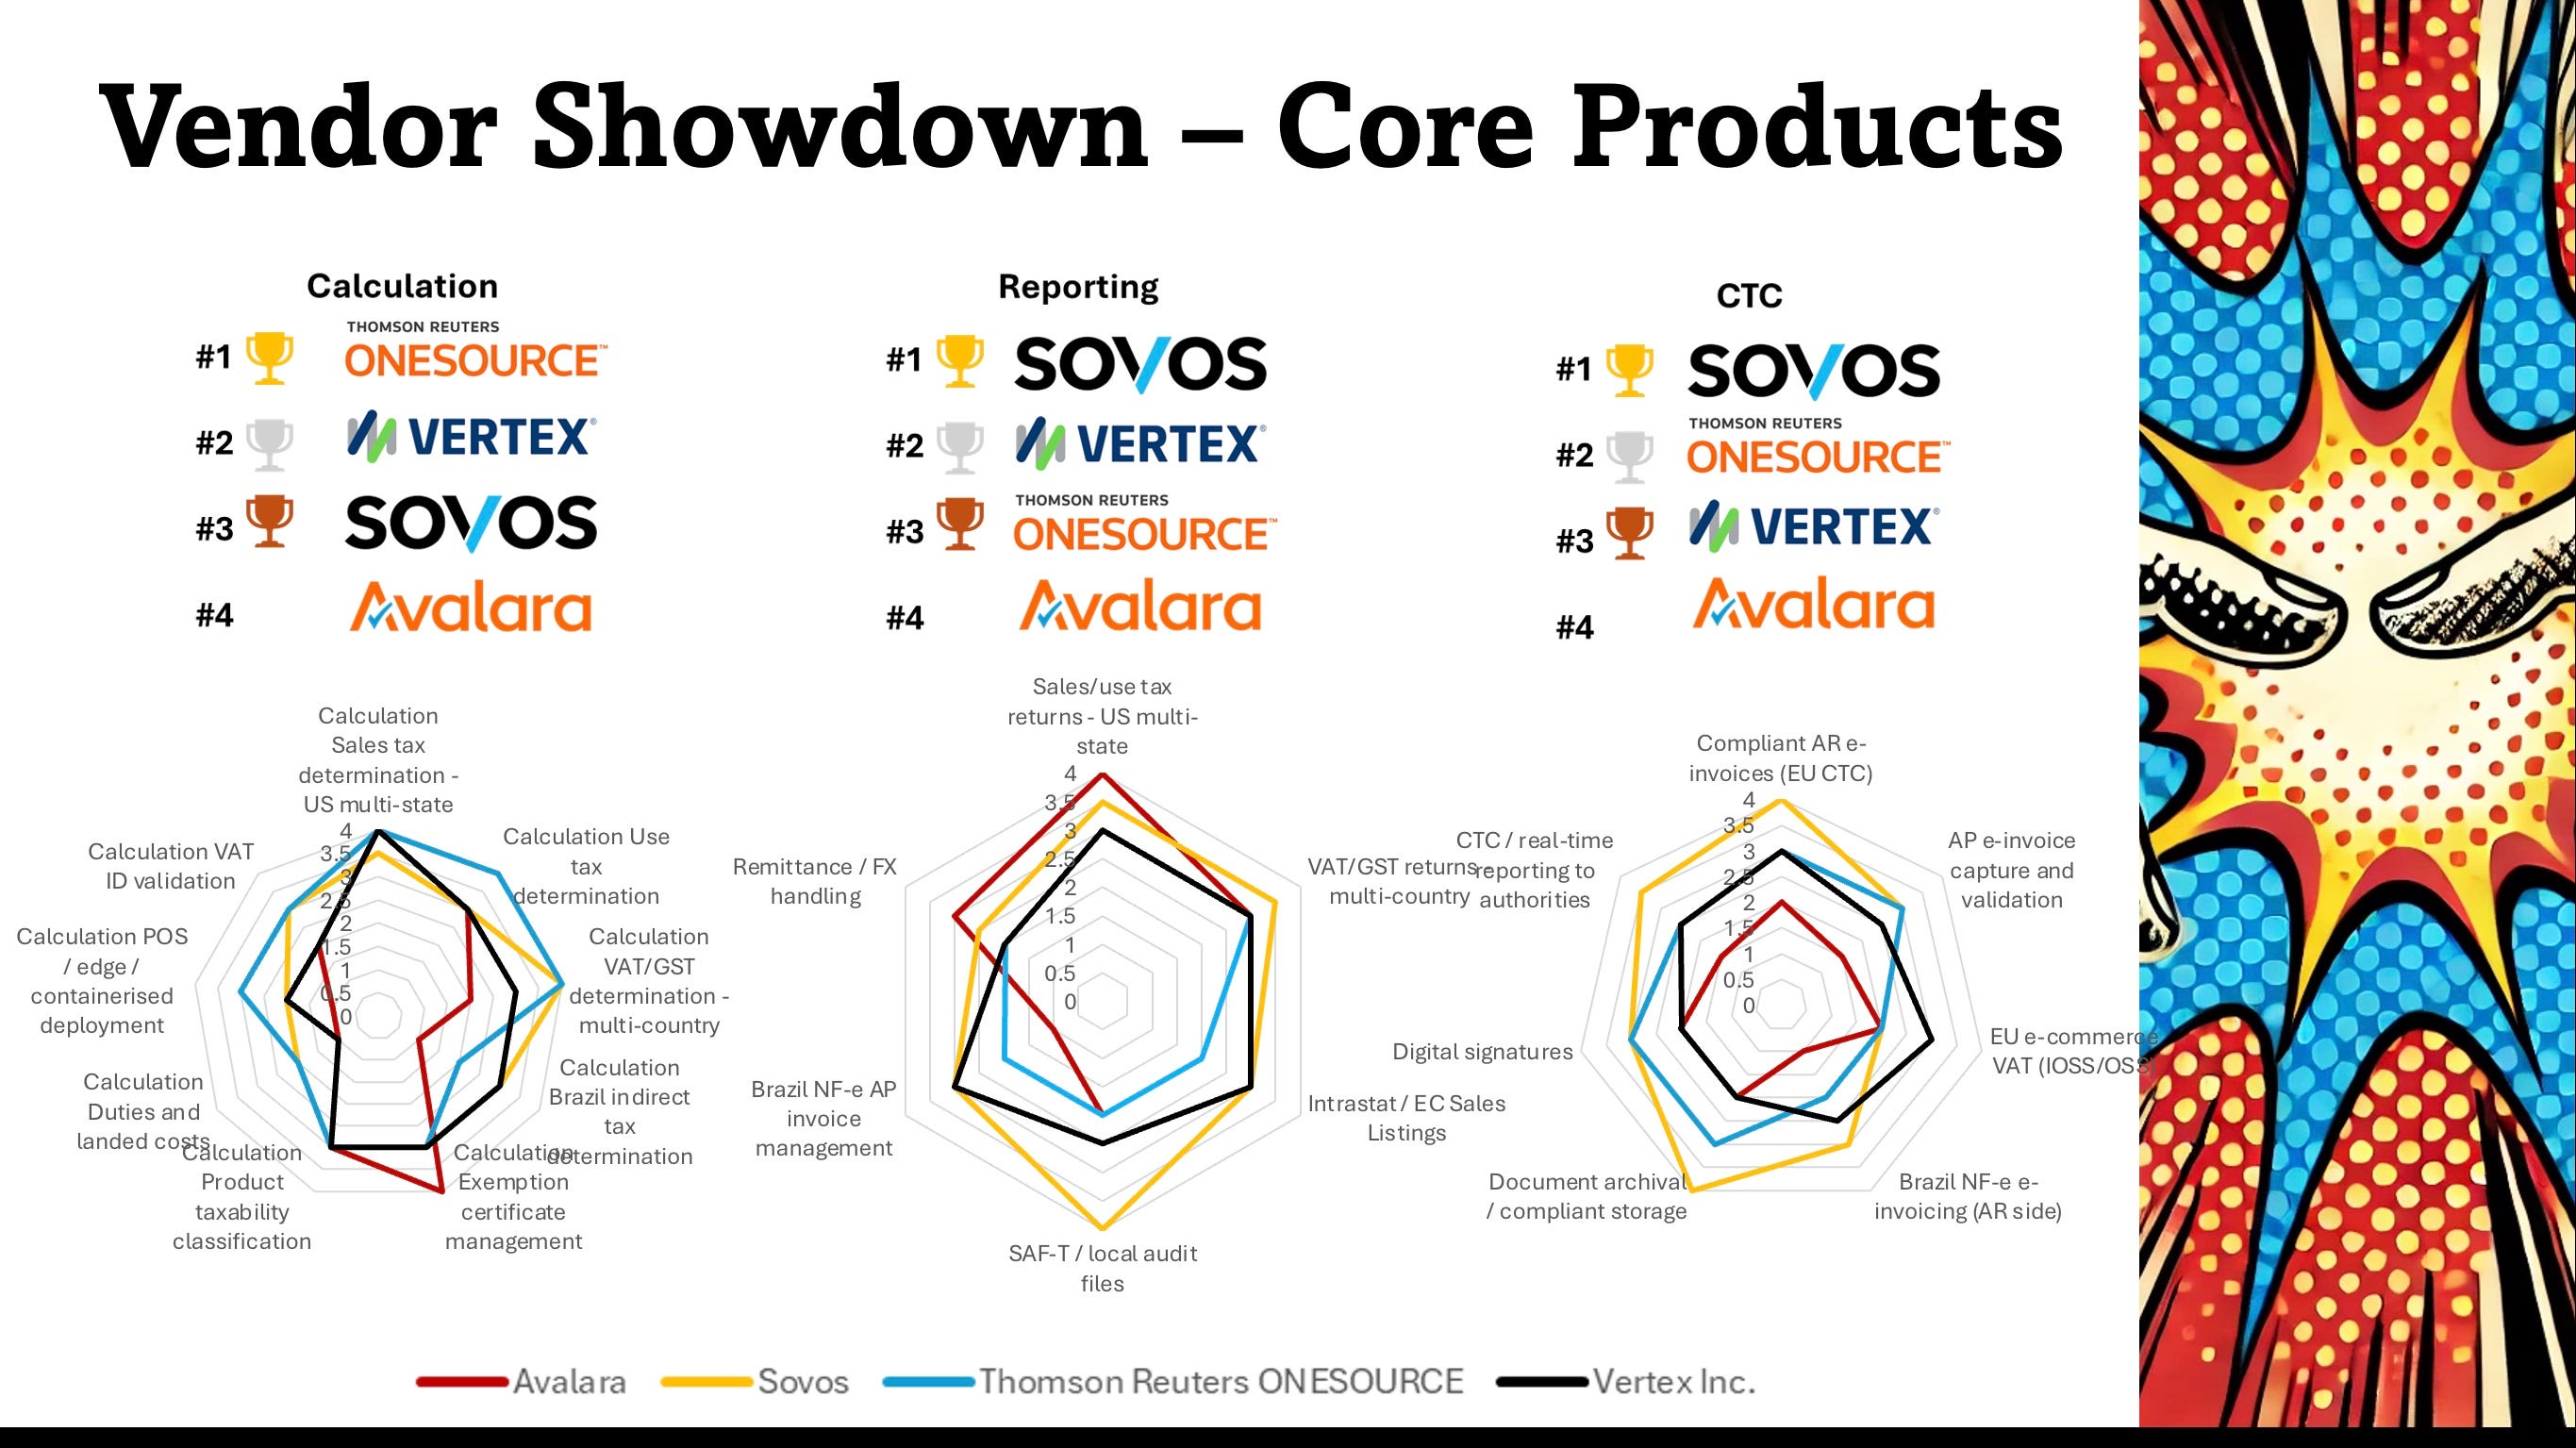
Thomson Reuters ONESOURCE leads decisively on calculation accuracy and vertical depth, volumetric excise, duty classification at jurisdictional granularity—these are capabilities that no other vendor in this peer group can credibly claim. If you operate in chemicals, oil and gas, or any heavily excised vertical, Thomson Reuters is the main credible candidate. The architecture is enterprise-grade and the editorial team behind content updates is unmatched. But that depth comes with breadth trade-offs: e-invoicing and CTC via the Pagero acquisition are genuine but still maturing. AI capability is functionally absent. The Deloitte managed services alliance (January 2026) is a structurally significant development in managed services this year—Big 4 delivery quality on Thomson Reuters infrastructure is genuinely differentiated—but it’s not a standalone BPO model.
Sovos leads on e-invoicing and CTC breadth. Sixty mandate countries with genuine operational maturity across LATAM (Brazil, Mexico, Colombia), Turkey, EU (Italy, Poland, Spain), and now APAC via IRIS. ViDA is not theory for them—they’ve been living it for years. SAF-T reporting is an explicit product differentiator. The platform handles complexity at scale that other vendors are still architecting. But VAT determination, while competent across 196 countries, is broad rather than deep—you won’t find Sovos in vertical niches the way you find Thomson Reuters. Architecture inconsistency across acquisitions surfaces as separate portals and uneven UX in reviews.
Avalara leads on integration ecosystem density. 1,200 pre-built connectors create a network effect that other vendors can’t replicate. For e-commerce platforms, accounting stacks, and high-volume transaction environments, Avalara‘s breadth is materially differentiated. For US SUT compliance at scale, it’s the clear winner. But that ecosystem is US-centric. International VAT determination is adequate but not specialist. CTC is nascent, not a scaled capability. The Versori acquisition targets connector scalability, not CTC country coverage.
Vertex leads on ERP integration maturity. Twenty-five years of SAP relationship DNA, 900 mutual SAP customers, SAP Endorsed App certification across three S/4HANA solutions. For organisations where the tax platform must sit inside SAP workflows and extend into PLUS Tools customisation, Vertex is structurally superior. US SUT calculation accuracy at Vertex is matched only by Thomson Reuters, and the Brazil O Series heritage via Systax is a structural advantage for LatAm operations. But reporting and analytics capability lags peers noticeably—this is the most consistent negative in G2 reviews.
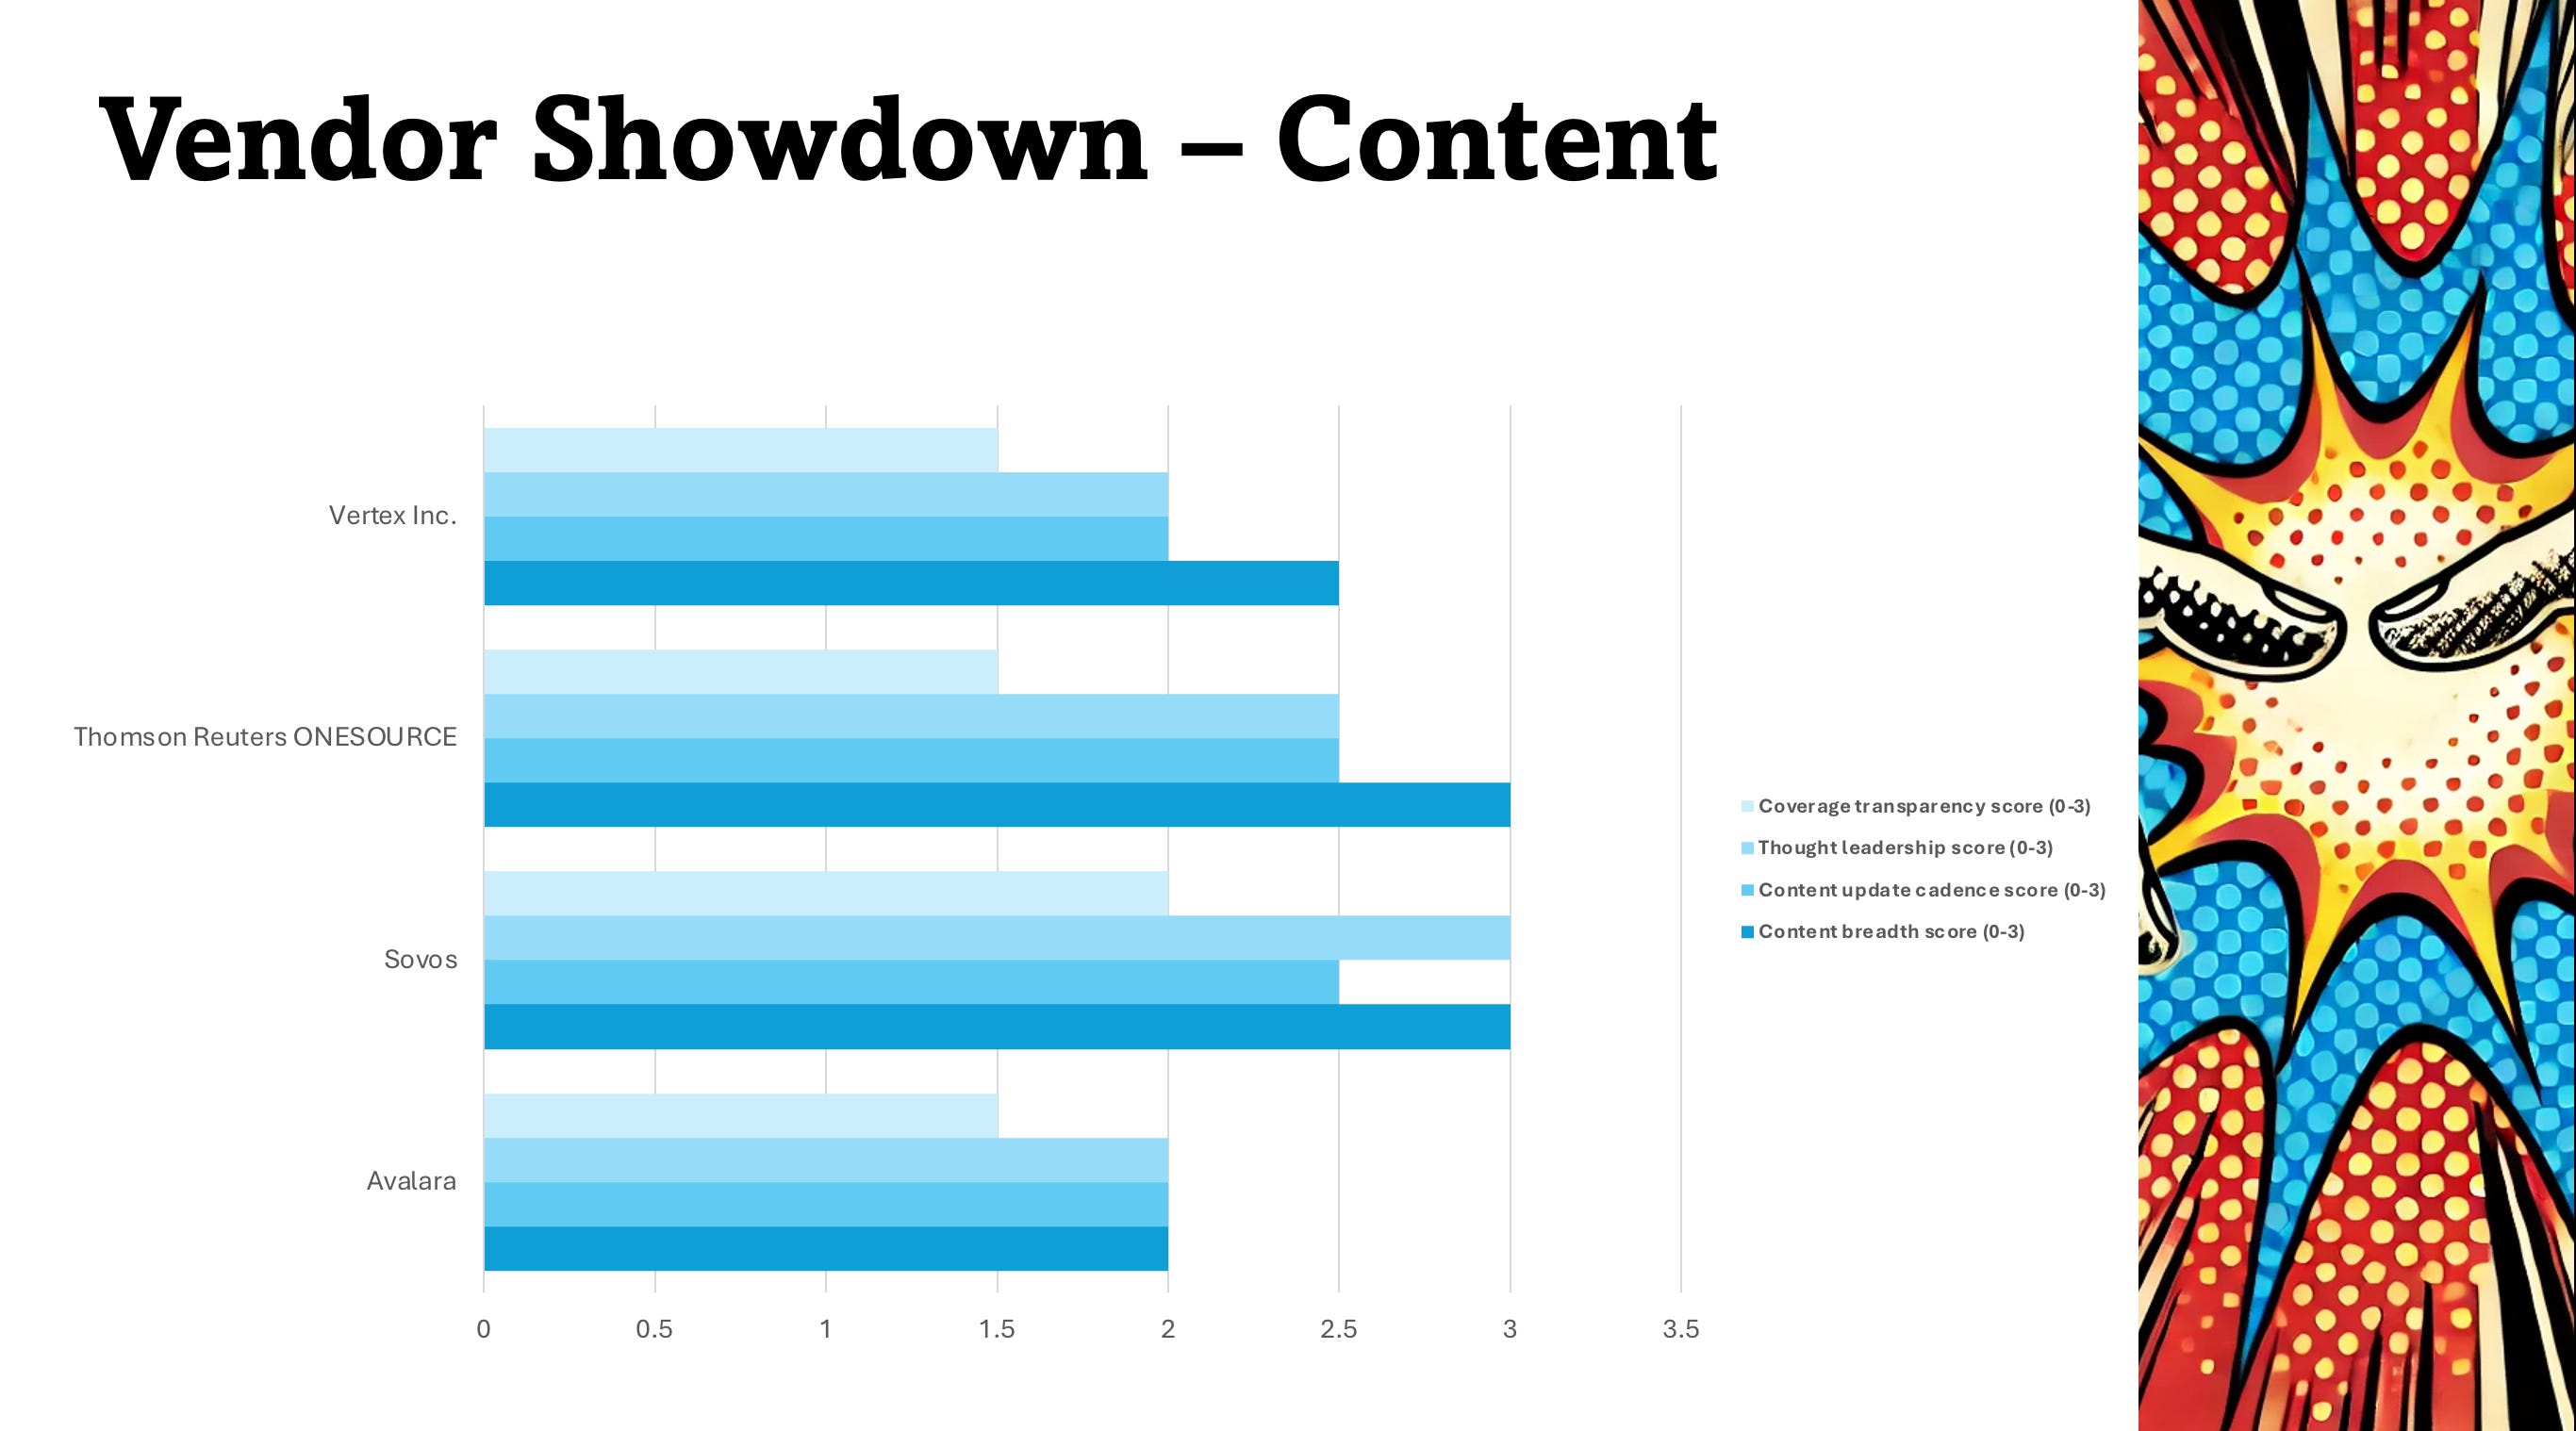
The best-fit vendor isn’t the one with the longest feature list. It’s the one whose specific strengths align with your actual compliance constraints. That alignment—not brand size or headline positioning—is what separates a strategic platform from an expensive disappointment.
Every vendor has an AI roadmap. None has delivered agentic tax workflows validated by independent customers as of April 2026. Avalara’s Avi platform is ambitious but carries no third-party validation. Vertex has a strong IP foundation but slowest product conversion. Sovos Intelligence is analytics-oriented, not agentic for now. Thomson Reuters has little publicly disclosed AI capability in indirect tax. Don’t factor AI into your business case. Treat it as a 12–24 month watch item.
FUNCTIONAL SHORTLIST: PRACTICAL GUIDANCE
If you’re a large multinational with SAP at your core, operating across 10+ VAT jurisdictions with CTC and SAF-T obligations: Vertex is the default if you want institutional sales org stability; Sovos is the alternative if you want global CTC breadth and don’t mind architectural integration work. Lock in renewal price caps and support continuity before signing with either.
If you’re mid-market and US-focused with strong e-commerce complexity: Avalara still owns the category. Structure your contract to cap pricing escalation and transaction-definition disputes. Document everything in the contract.
If you’re a mid-sized multinational with real international complexity and SAP dependency: Sovos or Thomson Reuters belong on your list. Budget 3–6 months for implementation and treat it as a platform change programme.
If you’re competing on multiple vendors and AI feels like a differentiator: Don’t weight it yet. All four are credible starting points. The real differentiator is ownership stability, support quality at your size tier, and specific product depth in your jurisdictions.
NEXT WEEK: BUSINESS MODEL FIT & THE REAL CUSTOMER STORY
Beyond product capabilities, your fit depends on three factors rarely discussed together: your business model (B2B goods, B2C goods, digital services, professional services), your company size (Small, Mid, Enterprise), and what actual customers and employees are experiencing.
Want a copy of the full 60+ page report?
🙌 May Events
A selection of of opportunities to connect in person and interact online over the next few weeks
May 2026
Deloitte Tax Accounting Conference (In-Person)
Deloitte | May 11–15, 2026 | Four Seasons Hotel, Las Vegas, Nevada, USA
Semiannual conference featuring sessions covering ASC 740 foundations, international tax accounting essentials, and complex domestic and global legislative changes. Includes dedicated courses on Tax Accounting Essentials (May 11–12), Tax Accounting International Essentials (May 13), and Tax Accounting Complexities (May 13–15).
Event Page →
SAP Sapphire Orlando 2026 (In-Person)
Vertex Inc | May 11–13, 2026 | Orlando, FL, USA
SAP’s flagship user conference featuring Vertex at Booth #343, plus a dedicated customer session on SAP tax transformation.
Register →
E-Invoicing: What Accounts Payable Teams Need to Know (Webinar)
VAT IT | May 12, 2026 | Online/Virtual
Overview of global e-invoicing mandates, upcoming country requirements, and practical compliance insights for accounts payable and business teams.
Register →
SYNAPSE Workshop SF 2026: Where Tax Meets Intelligence (In-Person)
Fonoa | May 12, 2026 | San Francisco, USA
Half-day session where indirect tax leaders explore the future of indirect tax, measure tax tech maturity, and network with peers in the digital economy.
Register →
Private Companies Tax Update: Pillar Two, GI3/R&D, and M&A (Webinar)
Deloitte | May 12, 2026 | Online/Virtual
Practical discussion on the next wave of tax changes impacting private companies, with a focus on Pillar Two, GI3/R&D credits, and M&A tax considerations.
Register →
DynamicsCon 2026 (In-Person)
Vertex Inc | May 12–15, 2026 | Las Vegas, USA
Conference where Vertex helps Dynamics 365 customers modernise indirect tax processes and boost compliance confidence across their operations.
Register →
Accountex (In-Person)
VAT IT | May 13–14, 2026 | ExCeL London, UK
Brings together tax and finance leaders to discuss UK developments, Making Tax Digital, and European initiatives including VAT in the Digital Age (ViDA).
Register →
Tax Accounting in Action: Pillar 2 Unlocked (In-Person)
Deloitte Belgium | May 18–19, 2026 | Belgium
A comprehensive two-day workshop focused on Pillar 2 tax accounting changes, their practical implications, and implementation strategies.
Event Page →
Join EY, Meridian, Jaguar Land Rover, and SAP: Exclusive Tax and Trade Leadership Event (In-Person)
EY / Meridian Global Services | May 19, 2026 | EY Offices, London Bridge, London, UK
Brings together industry peers to explore the evolving landscape of tax and trade, focusing on the latest trends and best practices in global compliance. Contact Ruby Buckland at EY to register.
Event Page →
Trade and Tariff Tuesdays — May (Webinar)
Avalara | May 19, 2026 | Online/Virtual
Avalara experts break down key global trade issues and their business implications in this recurring webinar series.
Register →
Tax Intelligence 2026 / Evintel (In-Person)
Fintua / VAT IT | May 20–21, 2026 | Scandic Frankfurt Museumsufer, Frankfurt, Germany
Specialist summit for senior tax and technology professionals exploring the challenges and opportunities of governing VAT data and e-invoicing at scale.
Event Page →
Gartner Finance Symposium/Xpo™ 2026 (In-Person)
Vertex Inc | May 27–29, 2026 | Gaylord National Resort, National Harbor, MD, USA
Finance leaders forum with Vertex providing practical strategies on indirect tax compliance within the enterprise technology ecosystem.
Register →
What to Expect from Global Tax Policy and Controversy in 2026 (Webinar)
EY | May 28, 2026 | Online/Virtual
A panel of EY Tax Policy and Controversy leaders discusses strategic priorities for tax departments as they address changing global tax policy and enforcement landscapes.
Register →
June 2026
Tax Tech Live 2026 (In-Person)
Tax Systems | June 2, 2026 | London, UK
Exclusive customer-focused event bringing together tax professionals for a day of cutting-edge insights, expert discussions, and the latest innovations in tax technology. Contact your Tax Systems Client Executive to register.
Event Page →
Private Equity & Private Capital Quarterly Tax Update — Q2 2026 (Webinar)
EY | June 4, 2026 | Online/Virtual
Quarterly update on strategic influences shaping private equity and capital funds, including US legislative updates, global macro trends, and tax implications.
Register →
*any organisers or events I’ve missed? please let me know.
🐱🏍 Learning
A curated selection of blogs, white-papers and on demand content published by multiple organisartions across the landscape, organised into a themed learning path.
MONTH TWO · MAY 2026
E-Invoicing, CTCs & Real-Time Compliance
Belgium is now live, Brazil is overhauling its entire indirect tax system, Poland’s KSeF mandate is entering enforcement, and France’s September 2026 deadline is approaching. The e-invoicing landscape has never moved faster.
Week 6 · 12–16 May
The European Mandate Wave: ViDA, Belgium Live, and What’s Next
This week has been updated to replace the KSeF-specific deep dive with a fresh analysis of Belgium’s live mandate, which went active on 1 January 2026 and entered full enforcement on 1 April 2026. The Belgium lessons are immediately applicable to the next wave of European mandates — France (September 2026), remaining German phase-in, and Croatia (2026).
16 📖 What is ViDA? VAT in the Digital Age Initiative Q&A Pagero (TR) 12–15 min
17 📖 5 Things We Can Learn from Belgium’s 2026 E-Invoicing Mandate Innovate Tax 8–10 min
18 🎥 VAT Snapshot: From Poland to the UAE — Preparing for 2026 Mandates Sovos 45–60 min
Week total: 2 articles + 1 webinar · ~65–85 min
Week 7 · 19–23 May
Platform Strategy: ERP Integration, Consolidation & Architecture
19 📖 Leading the Charge: E-Invoicing as the Cornerstone of Future Compliance Vertex Inc. 10–12 min
20 📖 E-Invoicing Transformation: How to Get It Right Pagero (TR)10–12 min
21 🎥 E-Invoicing in Eastern Europe: KSeF, ViDA, Romania, Hungary & Beyond Pagero (TR) 45 min
Week total: 2 articles + 1 webinar · ~65–69 min
Week 8 · 26–30 May
Intelligence & Emerging Markets: SYNAPSE Insights, Brazil’s Reform & AI in Indirect Tax
22 📖 5 Key Indirect Tax Trends from SYNAPSE 2026 Fonoa 10–12 min
23 📖 Brazil 2026 Tax Reform: Key E-Invoicing Changes for Businesses Fonoa 10–12 min
24 🎥 Embracing the Future of Tax Compliance with AI Avalara 45–60 min
Week total: 2 articles + 1 webinar · ~65–84 min
MONTH THREE · JUNE–JULY 2026
Direct Tax, Pillar Two & Corporate Tax Provision
The GIR filing window is now open — calendar-year groups face a June 30, 2026 deadline for their first live GloBE Information Return. The OECD Side-by-Side Package has materially changed what US-headquartered MNEs must do, but QDMTTs remain, GIR obligations continue, and non-US MNEs face unchanged IIR/UTPR exposure. This month goes deep on the technology implications of all of it.
Week 9 · 2–6 June
Pillar Two 2026: The Side-by-Side Package and What It Means for Technology
25 📖 QDMTT: Stay Ahead of the Global Minimum Tax Curve Orbitax (TR) 12–15 min
26 📖 OECD Side-by-Side Package: Relief for US Multinationals RSM US 12–15 min
27 🎥 Pillar Two Compliance: Grant Thornton & Orbitax Strategies Orbitax / Grant Thornton 60 min · CPE
Week total: 2 articles + 1 webinar · ~84–90 min
Month Two/Three total: 8 articles + 4 webinars · ~269–328 min
*any cool content I’ve missed? please let me know.
🎁 Open Taxtech Jobs
A randomised selection of open roles across tax tech vendors and tax advisory/consulting businesses who are involved in tax technology.
Use the column headers to sort, or the (new) search function and don’t forget to navigate multiple pages!
*I do this using an AI agent and due to the volume, I don’t check every link, so please let me know if any of these don’t work or have disappeared when you follow them.
✌ Last thoughts
Thanks again for reading! If you have any feedback, suggestions, want to contribute, share gossip or would like to work together in any way, email me here or hit the button below!